Pan Liner Market Outlook
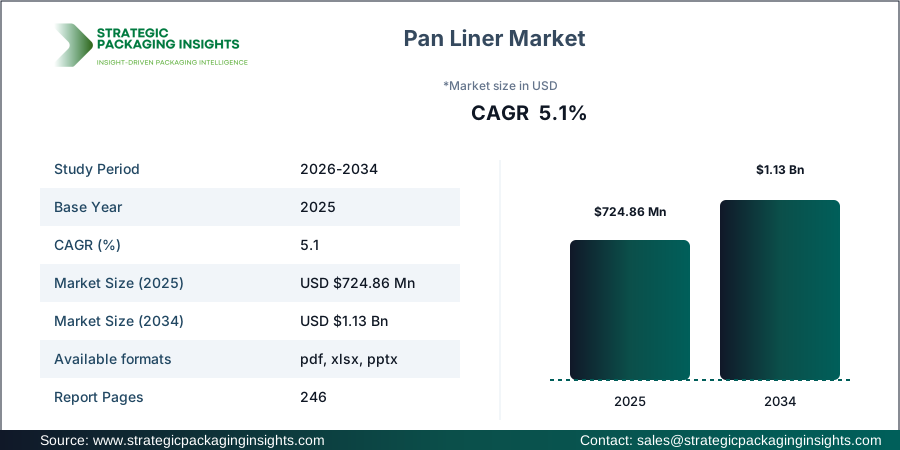
The Pan Liner market size was valued at USD 724.86 million in 2025 and is anticipated to reach USD 1.13 billion by 2034, growing at a CAGR of 5.1% during the forecast period according to Strategic Packaging Insights. The market is witnessing significant growth due to the increasing demand for convenient and efficient cooking solutions in both commercial and residential settings. Companies like Reynolds Consumer Products and Ahlstrom are leading the charge by innovating in product design and material technology, which is driving the market forward. The rise in home baking trends and the expansion of the foodservice industry are also contributing to the robust demand for pan liners.
One of the most impactful drivers of the Pan Liner market is the growing emphasis on sustainability and eco-friendly products. As consumers become more environmentally conscious, there is a heightened demand for products that minimize waste and reduce environmental impact. This trend is supported by government regulations and initiatives aimed at reducing single-use plastics and promoting sustainable packaging solutions. Companies like If You Care and Nordic Paper are at the forefront of this movement, offering products that align with these sustainability goals, thereby enhancing their market position and appeal to eco-conscious consumers.
Report Scope
| Attributes | Details |
| Report Title | Pan Liner Market Size, Future Growth and Forecast 2034 |
| Material Type | Parchment Paper, Silicone-Coated Paper, PTFE Liners, Aluminum Foil Liners |
| Product Type | Disposable Pan Liners, Reusable Pan Liners, Pre-Cut Liners |
| Application | Baking, Foodservice, Industrial Cooking |
| End Use | Bakeries, Restaurants, Food Processors, Households |
| Region | Asia Pacific, North America, Latin America, Europe, Middle East & Africa |
| Base Year | 2025 |
| Historic Period | 2018-2024 |
| Forecast Period | 2026-2034 |
| Number of Pages | 246 |
| Customization Available | Yes* |
Sustainability & Circular Economy Analysis
Sustainability initiatives are reshaping the Pan Liner market, with a strong focus on recyclable materials and eco-friendly innovations. Companies are increasingly adopting lightweight packaging solutions to reduce material usage and carbon footprint. The integration of recyclable and biodegradable materials is becoming a standard practice, driven by consumer demand for sustainable products. This shift is influencing packaging design and manufacturing processes, encouraging companies to invest in research and development to create more sustainable solutions.
The circular economy is gaining traction in the packaging industry, with extended producer responsibility (EPR) and waste reduction strategies playing a crucial role. Companies are implementing closed-loop systems to ensure that packaging materials are reused and recycled, minimizing waste and environmental impact. This approach not only aligns with regulatory compliance but also enhances brand reputation and competitiveness in the market. As a result, companies are prioritizing sustainability in their investment decisions and supply chain strategies.
Consumer preferences for sustainable packaging are driving regulatory changes and influencing market dynamics. Governments are introducing stricter packaging regulations to promote sustainability and reduce environmental impact. This regulatory landscape is pushing companies to innovate and adopt eco-friendly practices to remain competitive. The focus on sustainability is also impacting long-term market competitiveness, as companies that prioritize eco-friendly solutions are better positioned to meet evolving consumer demands and regulatory requirements.
Packaging Value Chain & Supply Chain Analysis
The packaging value chain for pan liners involves a complex ecosystem of raw material sourcing, manufacturing, and distribution. Raw material availability, particularly for sustainable and eco-friendly materials, is a critical factor influencing the supply chain. Packaging converters and manufacturers are focusing on optimizing production capabilities to meet the growing demand for pan liners. Strategic partnerships with suppliers and logistics providers are essential to ensure a steady supply of materials and efficient distribution channels.
Supply chain efficiency is paramount in the Pan Liner market, with companies investing in advanced packaging machinery and technologies to enhance production processes. Inventory management and procurement strategies are being optimized to reduce costs and improve supply chain resilience. Localization of production facilities is becoming increasingly important to mitigate risks associated with global sourcing and transportation. This trend is driven by the need to reduce lead times and enhance responsiveness to market demands.
Recycling networks and sustainable procurement practices are integral to the packaging value chain, as companies strive to minimize environmental impact and comply with regulatory requirements. The focus on sustainability is influencing supply chain strategies, with companies prioritizing eco-friendly materials and processes. This shift is enhancing overall market performance and competitiveness, as companies that adopt sustainable practices are better positioned to meet consumer expectations and regulatory standards.
Opportunities & Threats
The Pan Liner market presents numerous opportunities for growth, driven by the increasing demand for convenient and efficient cooking solutions. The rise in home baking trends and the expansion of the foodservice industry are creating new avenues for market expansion. Companies can capitalize on these opportunities by innovating in product design and material technology to meet evolving consumer needs. The growing emphasis on sustainability and eco-friendly products also presents significant opportunities for companies to differentiate themselves in the market.
Another opportunity lies in the development of new applications for pan liners, particularly in industrial cooking and food processing. As the food industry continues to evolve, there is a growing need for specialized packaging solutions that enhance efficiency and reduce waste. Companies that can develop innovative products to meet these needs are well-positioned to capture a larger share of the market. Additionally, the increasing adoption of digital technologies in packaging design and manufacturing offers opportunities for companies to enhance their production capabilities and improve supply chain efficiency.
However, the Pan Liner market also faces several threats, including regulatory challenges and competition from alternative packaging solutions. Stricter packaging regulations and environmental standards are increasing compliance costs for companies, which could impact profitability. Additionally, the availability of alternative packaging solutions, such as reusable containers and biodegradable materials, poses a threat to traditional pan liners. Companies must continuously innovate and adapt to changing market conditions to remain competitive and mitigate these threats.
Drivers & Challenges
One of the primary drivers of the Pan Liner market is the increasing demand for convenient and efficient cooking solutions. The rise in home baking trends and the expansion of the foodservice industry are contributing to the robust demand for pan liners. Companies like Reynolds Consumer Products and Ahlstrom are leading the charge by innovating in product design and material technology, which is driving the market forward. The growing emphasis on sustainability and eco-friendly products is also a significant driver, as consumers become more environmentally conscious and seek products that minimize waste and reduce environmental impact.
Another key driver is the growing emphasis on sustainability and eco-friendly products. As consumers become more environmentally conscious, there is a heightened demand for products that minimize waste and reduce environmental impact. This trend is supported by government regulations and initiatives aimed at reducing single-use plastics and promoting sustainable packaging solutions. Companies like If You Care and Nordic Paper are at the forefront of this movement, offering products that align with these sustainability goals, thereby enhancing their market position and appeal to eco-conscious consumers.
Despite these drivers, the Pan Liner market faces several challenges, including regulatory challenges and competition from alternative packaging solutions. Stricter packaging regulations and environmental standards are increasing compliance costs for companies, which could impact profitability. Additionally, the availability of alternative packaging solutions, such as reusable containers and biodegradable materials, poses a threat to traditional pan liners. Companies must continuously innovate and adapt to changing market conditions to remain competitive and mitigate these challenges.
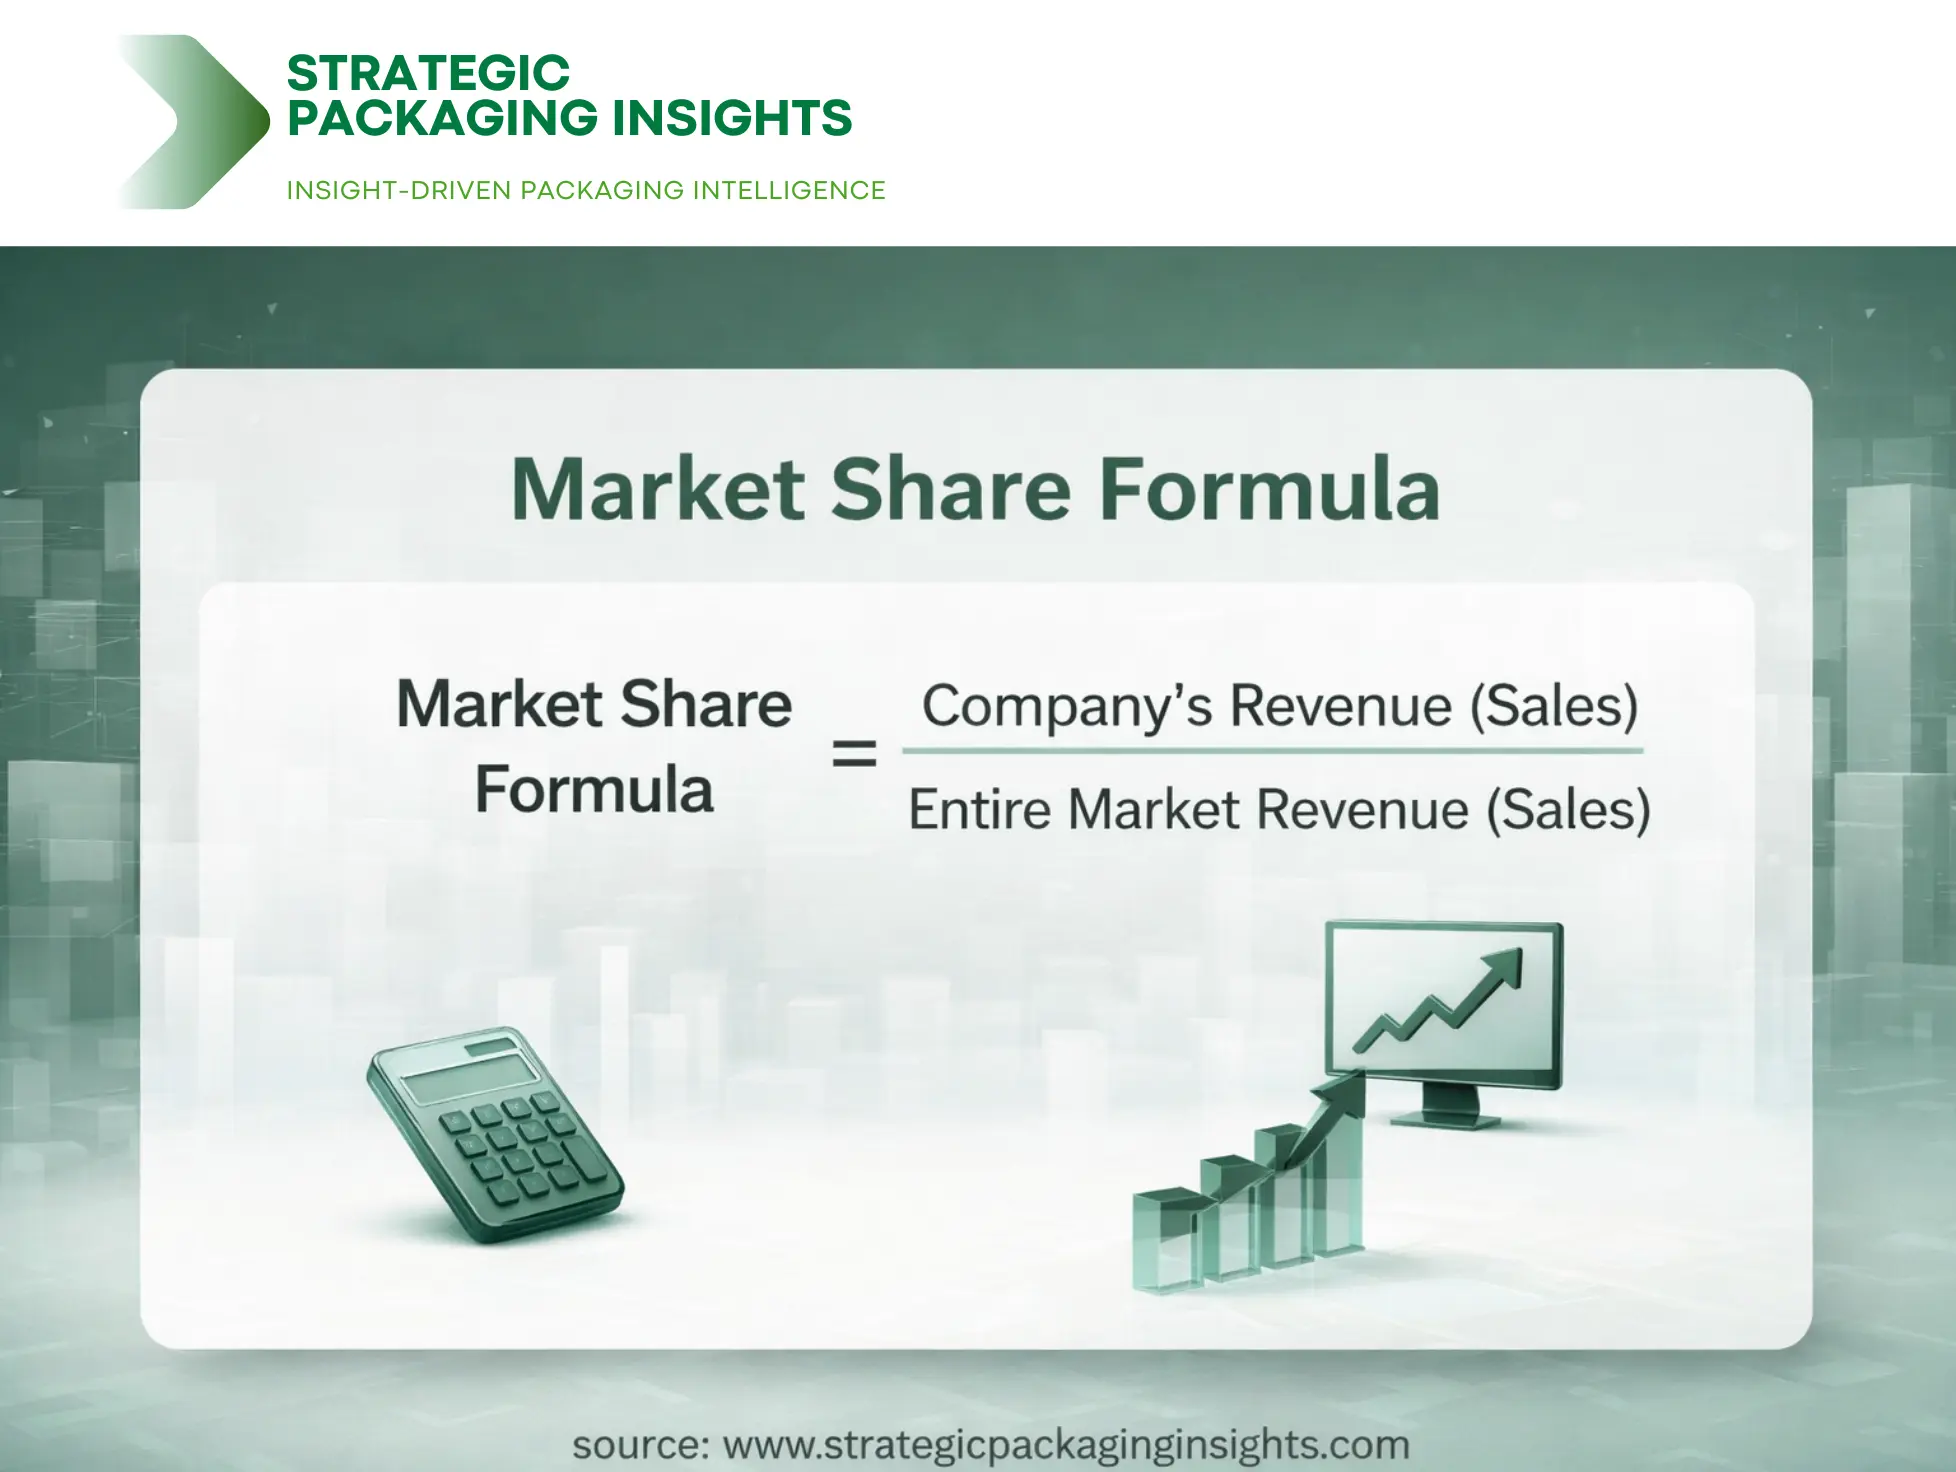
Market Share Analysis
The Pan Liner market is characterized by a competitive landscape with several key players vying for market share. Companies like Reynolds Consumer Products, Ahlstrom, and Nordic Paper are leading the market with their innovative product offerings and strong brand presence. These companies have established themselves as leaders in the market by focusing on product innovation, sustainability, and customer satisfaction. Their ability to adapt to changing market conditions and consumer preferences has enabled them to maintain a competitive edge.
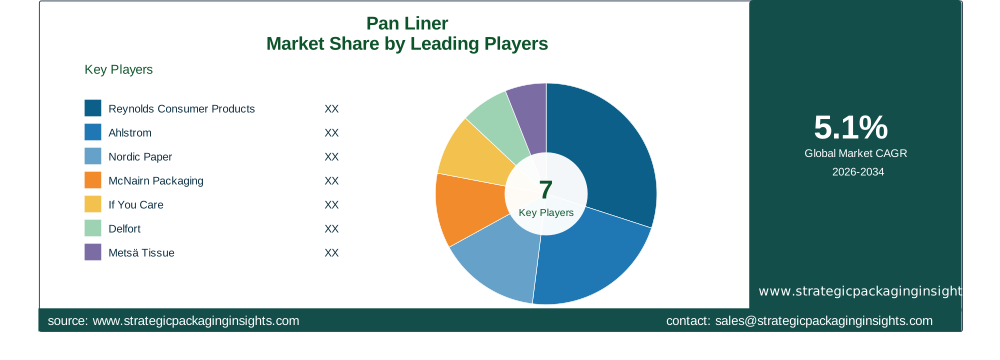
Reynolds Consumer Products is a major player in the Pan Liner market, known for its high-quality products and strong brand reputation. The company has a diverse product portfolio that caters to various consumer needs, from disposable pan liners to eco-friendly options. Ahlstrom, on the other hand, is recognized for its focus on sustainability and innovation. The company's commitment to developing eco-friendly products has positioned it as a leader in the market, appealing to environmentally conscious consumers.
Nordic Paper is another key player in the market, known for its high-quality parchment paper products. The company's focus on sustainability and innovation has enabled it to capture a significant share of the market. McNairn Packaging and If You Care are also notable players, offering a range of eco-friendly pan liner products that cater to the growing demand for sustainable packaging solutions. These companies have established themselves as leaders in the market by focusing on product innovation, sustainability, and customer satisfaction.
Other significant players in the market include Delfort, Metsä Tissue, Krpa Paper, Sappi, and Mondi. These companies have a strong presence in the market, offering a range of products that cater to various consumer needs. Their focus on sustainability and innovation has enabled them to maintain a competitive edge in the market. As the market continues to evolve, these companies are well-positioned to capitalize on emerging opportunities and address the challenges posed by changing consumer preferences and regulatory requirements.
Key Highlights
- Market Size: The Pan Liner market was valued at USD 724.86 million in 2025 and is projected to reach USD 1.13 billion by 2034.
- Growth Rate: The market is expected to grow at a CAGR of 5.1% during the forecast period.
- Leading Companies: Key players include Reynolds Consumer Products, Ahlstrom, and Nordic Paper.
- Material Type: Parchment Paper and Silicone-Coated Paper are prominent segments.
- Product Type: Disposable Pan Liners dominate the market.
- Application: Baking and Foodservice are major application areas.
- Region: North America and Europe are leading regions in the market.
Pan Liner Market Segments Insights
Material Type Analysis
The Pan Liner market is segmented by material type into Parchment Paper, Silicone-Coated Paper, PTFE Liners, and Aluminum Foil Liners. Parchment Paper is a popular choice due to its non-stick properties and versatility in baking and cooking applications. It is favored by both commercial and residential users for its ease of use and ability to withstand high temperatures. Silicone-Coated Paper is gaining traction for its durability and reusable nature, appealing to environmentally conscious consumers. PTFE Liners and Aluminum Foil Liners are also significant segments, offering unique benefits such as heat resistance and moisture barrier properties.
Innovation in material technology is driving growth in this segment, with companies investing in research and development to create more sustainable and efficient products. The demand for eco-friendly materials is influencing product design and manufacturing processes, encouraging companies to adopt sustainable practices. As a result, the material type segment is expected to witness significant growth during the forecast period, driven by consumer demand for sustainable and high-performance products.
Product Type Analysis
The product type segment of the Pan Liner market includes Disposable Pan Liners, Reusable Pan Liners, and Pre-Cut Liners. Disposable Pan Liners dominate the market due to their convenience and ease of use, particularly in commercial settings such as restaurants and bakeries. Reusable Pan Liners are gaining popularity among environmentally conscious consumers who seek sustainable alternatives to single-use products. Pre-Cut Liners offer convenience and time-saving benefits, appealing to both commercial and residential users.
Companies are focusing on product innovation to meet evolving consumer needs, with an emphasis on sustainability and eco-friendly solutions. The development of new materials and designs is enhancing the performance and appeal of pan liners, driving growth in this segment. As consumer preferences shift towards sustainable and convenient solutions, the product type segment is expected to experience robust growth during the forecast period.
Application Analysis
The application segment of the Pan Liner market includes Baking, Foodservice, and Industrial Cooking. Baking is a major application area, driven by the rise in home baking trends and the expansion of the foodservice industry. Pan liners are essential in baking applications, providing non-stick properties and ease of cleanup. The Foodservice segment is also significant, with restaurants and catering services relying on pan liners for efficient and hygienic food preparation.
Industrial Cooking is an emerging application area, with pan liners offering benefits such as heat resistance and moisture barrier properties. Companies are developing specialized products to meet the needs of industrial cooking applications, driving growth in this segment. As the food industry continues to evolve, the application segment is expected to witness significant growth, driven by the demand for efficient and sustainable cooking solutions.
End Use Analysis
The end use segment of the Pan Liner market includes Bakeries, Restaurants, Food Processors, and Households. Bakeries and Restaurants are major end users, relying on pan liners for efficient and hygienic food preparation. The rise in home baking trends is driving demand in the Household segment, with consumers seeking convenient and efficient cooking solutions. Food Processors are also significant end users, utilizing pan liners for industrial cooking applications.
Companies are focusing on developing products that cater to the specific needs of each end use segment, with an emphasis on sustainability and performance. The demand for eco-friendly and high-performance products is influencing product design and manufacturing processes, driving growth in this segment. As consumer preferences shift towards sustainable and convenient solutions, the end use segment is expected to experience robust growth during the forecast period.
Pan Liner Market Segments
The Pan Liner market has been segmented on the basis ofMaterial Type
- Parchment Paper
- Silicone-Coated Paper
- PTFE Liners
- Aluminum Foil Liners
Product Type
- Disposable Pan Liners
- Reusable Pan Liners
- Pre-Cut Liners
Application
- Baking
- Foodservice
- Industrial Cooking
End Use
- Bakeries
- Restaurants
- Food Processors
- Households
Region
- Asia Pacific
- North America
- Latin America
- Europe
- Middle East & Africa