Assembly Trays Market Outlook
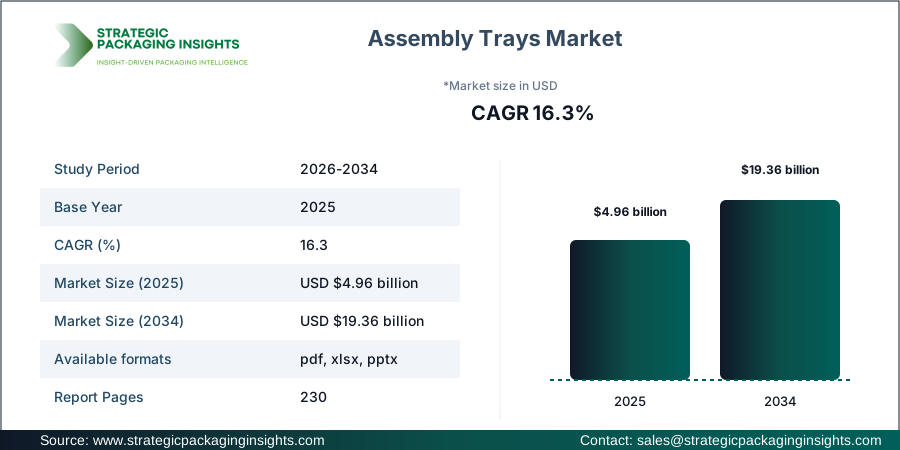
The Assembly Trays market was valued at $4.96 billion in 2025 and is projected to reach $19.36 billion by 2034, growing at a CAGR of 16.3% during the forecast period 2026-2034. This robust growth trajectory is driven by the increasing demand for efficient and reliable packaging solutions across various industries, including electronics, automotive, and healthcare. The market's expansion is further fueled by advancements in material technology, which have led to the development of more durable and versatile tray options. As industries continue to prioritize operational efficiency and product safety, the demand for high-quality assembly trays is expected to rise significantly.
Despite the promising growth prospects, the Assembly Trays market faces certain challenges that could hinder its expansion. Regulatory constraints related to material usage and environmental concerns are among the primary restraining factors. Additionally, the market is highly competitive, with numerous players vying for market share, which could lead to pricing pressures. However, the increasing focus on sustainable and eco-friendly packaging solutions presents significant growth potential for market players willing to innovate and adapt to changing consumer preferences. As the market evolves, companies that can effectively balance cost, quality, and sustainability are likely to emerge as leaders in the industry.
Report Scope
| Attributes | Details |
| Report Title | Assembly Trays Market Size, Future Growth and Forecast 2034 |
| Product Type | Plastic Assembly Trays, Metal Trays, ESD Trays, Custom Trays |
| Material Type | PP, ABS, Stainless Steel, Conductive Polymers |
| Application | Electronics Assembly, Automotive Parts, Medical Devices, Industrial Components |
| End Use | OEMs, Contract Manufacturers, Workshops, Warehouses |
| Region | Asia Pacific, North America, Latin America, Europe, Middle East & Africa |
| Base Year | 2025 |
| Historic Period | 2018-2024 |
| Forecast Period | 2026-2034 |
| Number of Pages | 230 |
| Customization Available | Yes* |
Opportunities & Threats
The Assembly Trays market presents numerous opportunities for growth, particularly in the realm of technological advancements and material innovations. As industries such as electronics and automotive continue to evolve, there is a growing need for specialized trays that can accommodate complex components and assemblies. This demand is driving innovation in tray design and material selection, with companies investing in research and development to create more efficient and effective solutions. Additionally, the increasing emphasis on sustainability and environmental responsibility is opening up new avenues for growth, as consumers and businesses alike seek out eco-friendly packaging options. Companies that can offer sustainable tray solutions without compromising on quality or performance are well-positioned to capitalize on this trend.
Another significant opportunity lies in the expansion of the global manufacturing sector, particularly in emerging markets. As countries in Asia Pacific, Latin America, and Africa continue to industrialize, the demand for assembly trays is expected to rise in tandem with the growth of manufacturing activities. This presents a lucrative opportunity for companies to expand their market presence and tap into new customer bases. Furthermore, the increasing adoption of automation and robotics in manufacturing processes is driving the need for precision-engineered trays that can support automated assembly lines. Companies that can provide customized solutions to meet the specific needs of automated systems are likely to gain a competitive edge in the market.
However, the Assembly Trays market is not without its threats. One of the primary challenges facing the industry is the volatility of raw material prices, which can significantly impact production costs and profit margins. Additionally, the market is subject to stringent regulatory requirements, particularly concerning the use of certain materials and the environmental impact of production processes. Companies must navigate these regulatory landscapes carefully to avoid potential fines and reputational damage. Moreover, the increasing competition in the market poses a threat to smaller players, who may struggle to compete with larger, more established companies with greater resources and market reach.
Drivers & Challenges
The Assembly Trays market is driven by several key factors, including the growing demand for efficient and reliable packaging solutions across various industries. As manufacturers seek to optimize their production processes and ensure the safe transport of components, the need for high-quality assembly trays has become increasingly apparent. This demand is particularly pronounced in the electronics and automotive sectors, where precision and reliability are paramount. Additionally, advancements in material technology have enabled the development of more durable and versatile trays, further driving market growth. The increasing focus on sustainability and eco-friendly packaging solutions is also a significant driver, as companies strive to meet consumer expectations and regulatory requirements.
Another major driver of the Assembly Trays market is the rapid expansion of the global manufacturing sector. As countries in Asia Pacific, Latin America, and Africa continue to industrialize, the demand for assembly trays is expected to rise in tandem with the growth of manufacturing activities. This presents a lucrative opportunity for companies to expand their market presence and tap into new customer bases. Furthermore, the increasing adoption of automation and robotics in manufacturing processes is driving the need for precision-engineered trays that can support automated assembly lines. Companies that can provide customized solutions to meet the specific needs of automated systems are likely to gain a competitive edge in the market.
Despite these drivers, the Assembly Trays market faces several challenges that could hinder its growth. One of the primary challenges is the volatility of raw material prices, which can significantly impact production costs and profit margins. Additionally, the market is subject to stringent regulatory requirements, particularly concerning the use of certain materials and the environmental impact of production processes. Companies must navigate these regulatory landscapes carefully to avoid potential fines and reputational damage. Moreover, the increasing competition in the market poses a threat to smaller players, who may struggle to compete with larger, more established companies with greater resources and market reach.
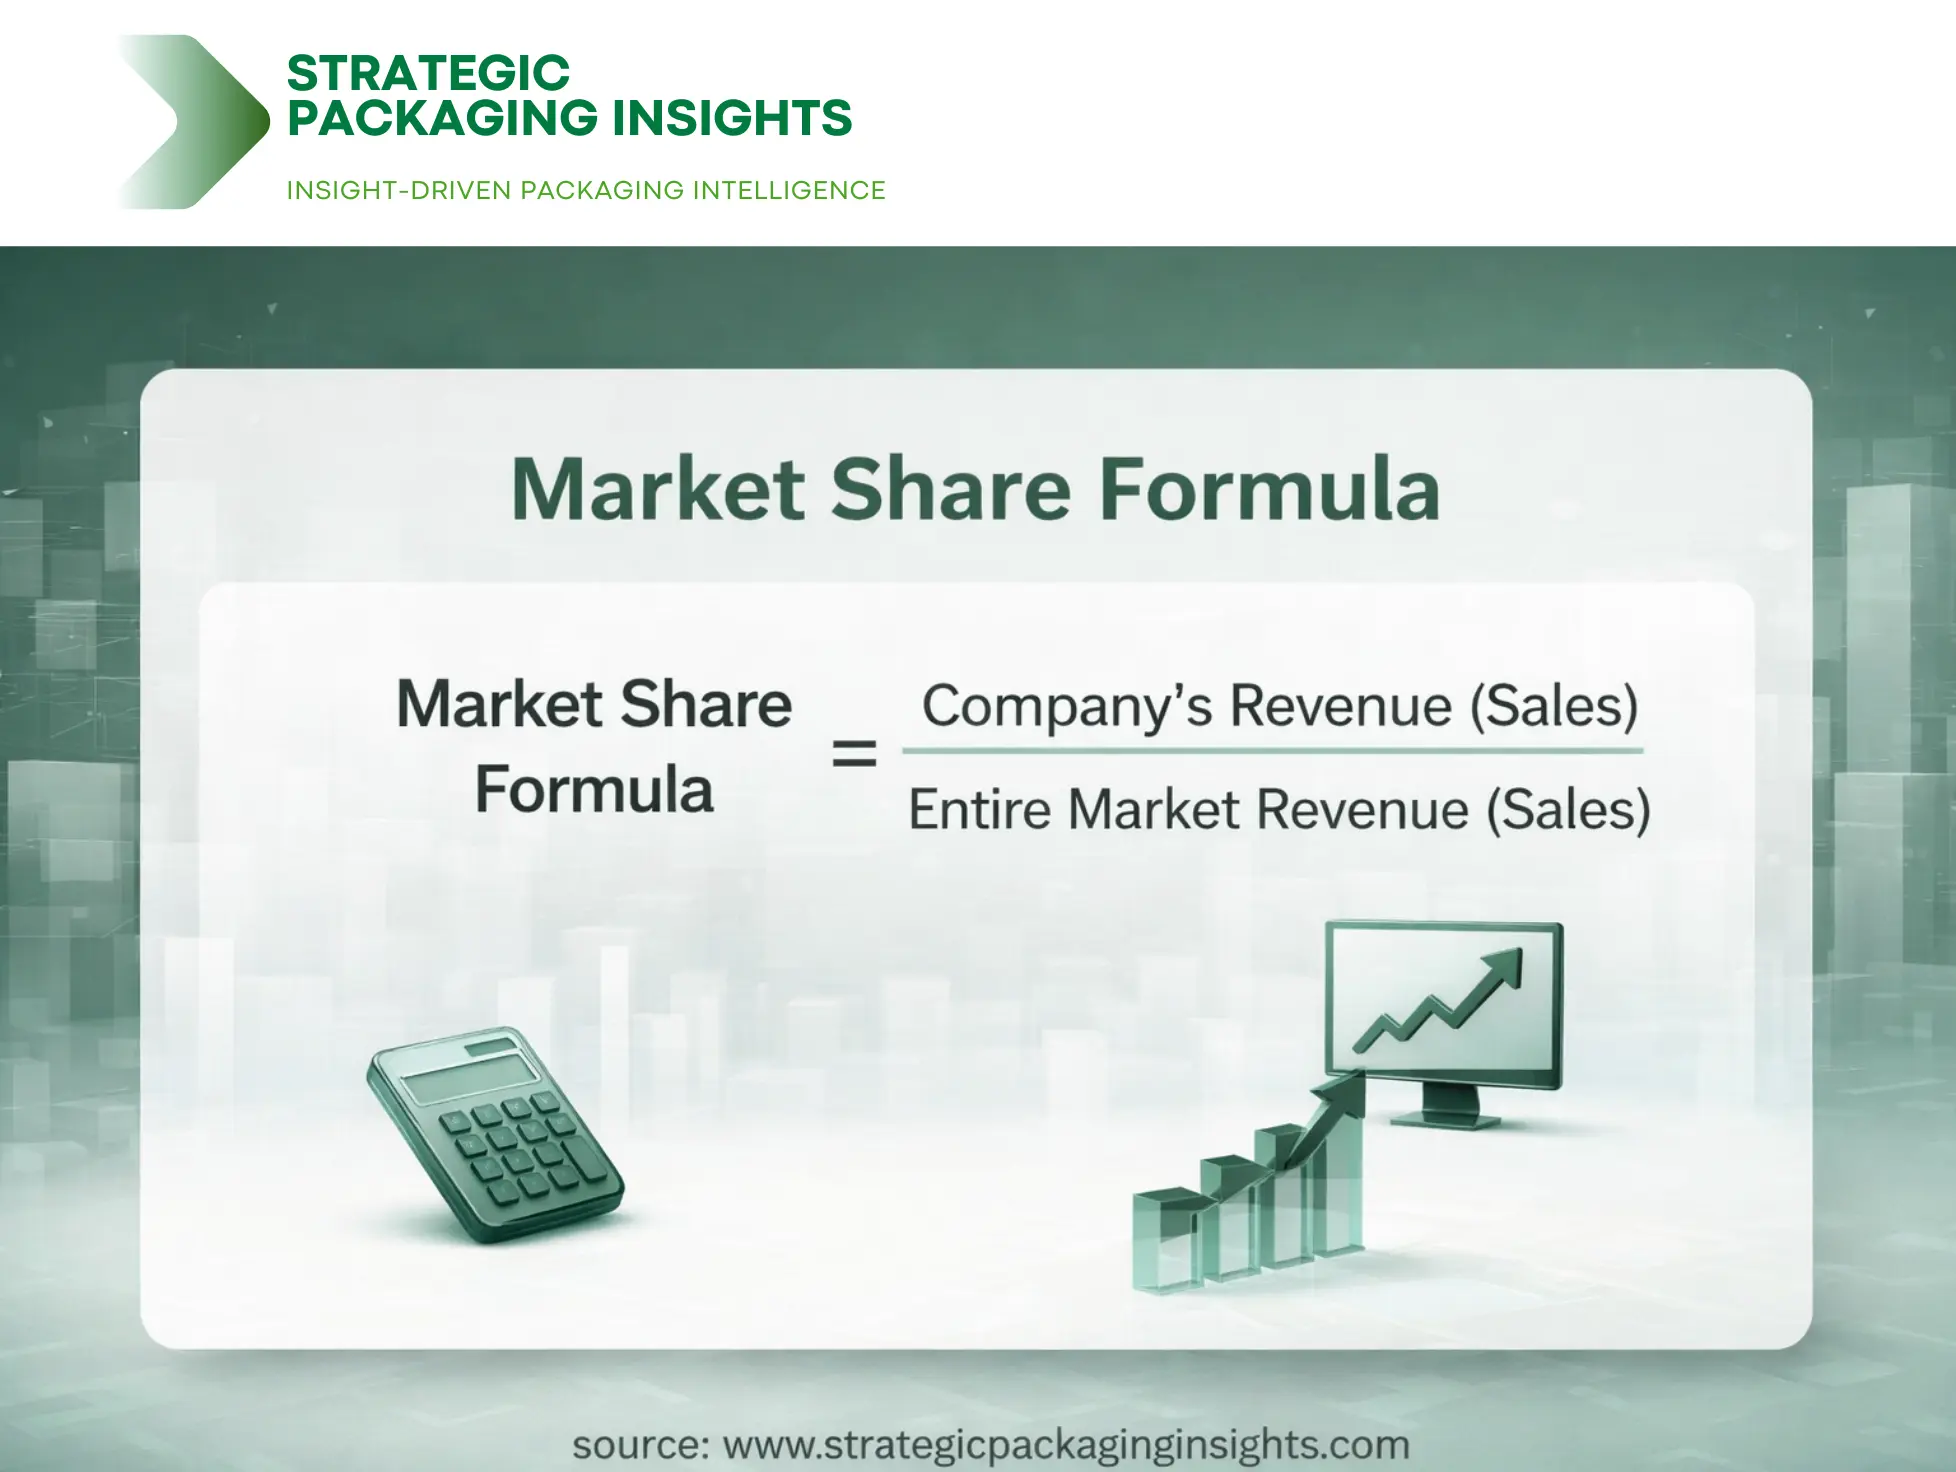
Market Share Analysis
The competitive landscape of the Assembly Trays market is characterized by the presence of several key players, each vying for a share of the growing market. Companies such as UFP Technologies, Sonoco Products Company, and Placon are among the leading players, leveraging their extensive experience and broad product portfolios to maintain a competitive edge. These companies have established themselves as leaders in the industry by consistently delivering high-quality products and innovative solutions that meet the evolving needs of their customers. Additionally, their strong distribution networks and strategic partnerships have enabled them to expand their market reach and capitalize on emerging opportunities.
UFP Technologies, for instance, holds a significant market share due to its focus on innovation and customer-centric solutions. The company has invested heavily in research and development to create advanced tray designs that cater to the specific needs of various industries. Similarly, Sonoco Products Company has leveraged its extensive experience in packaging solutions to offer a diverse range of assembly trays that meet the highest standards of quality and performance. The company's commitment to sustainability and eco-friendly practices has also resonated well with environmentally conscious consumers, further bolstering its market position.
Placon, another major player in the Assembly Trays market, has distinguished itself through its focus on customization and flexibility. The company offers a wide range of tray options that can be tailored to meet the unique requirements of its customers, providing a competitive advantage in a market where customization is increasingly valued. Prent Corporation and Nelipak are also notable players, known for their expertise in medical and electronics packaging solutions. These companies have built strong reputations for delivering reliable and innovative products that meet the stringent demands of their respective industries.
Other significant players in the market include Brentwood Industries, Penda, Universal Plastics, Flexcon, and ORBIS Corporation. Each of these companies has carved out a niche in the market by focusing on specific segments or applications, allowing them to effectively compete with larger, more diversified players. Brentwood Industries, for example, has gained recognition for its expertise in industrial components, while Penda is known for its durable and versatile tray solutions. As the market continues to evolve, these companies are likely to play a crucial role in shaping its future trajectory.
Key Highlights
- The Assembly Trays market is projected to grow from $4.96 billion in 2025 to $19.36 billion by 2034, at a CAGR of 16.3%.
- Key drivers include the demand for efficient packaging solutions and advancements in material technology.
- Regulatory constraints and raw material price volatility pose significant challenges.
- UFP Technologies, Sonoco Products Company, and Placon are leading players in the market.
- Customization and sustainability are emerging as key trends in the industry.
- The market is highly competitive, with numerous players vying for market share.
- Emerging markets in Asia Pacific and Latin America present significant growth opportunities.
- Automation and robotics in manufacturing are driving demand for precision-engineered trays.
- Environmental concerns are prompting a shift towards eco-friendly packaging solutions.
- Companies that can balance cost, quality, and sustainability are likely to succeed.
Top Countries Insights
In the Assembly Trays market, the United States stands out as a key player, with a market size of approximately $3.5 billion and a CAGR of 12%. The country's strong manufacturing base and emphasis on technological innovation drive demand for advanced assembly trays. Additionally, the U.S. government's focus on promoting domestic manufacturing and reducing reliance on imports further supports market growth. However, regulatory challenges related to environmental standards and material usage remain a concern for manufacturers operating in the region.
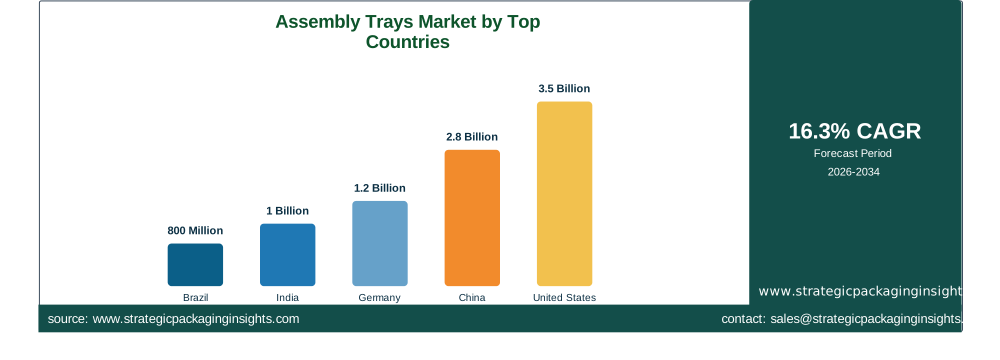
China is another significant market, with a current size of $2.8 billion and a CAGR of 18%. The country's rapid industrialization and expanding electronics and automotive sectors are major growth drivers. China's government policies aimed at boosting domestic manufacturing and exports also contribute to the market's expansion. However, the market faces challenges related to quality control and the need for compliance with international standards, which can impact the competitiveness of Chinese manufacturers on the global stage.
Germany, with a market size of $1.2 billion and a CAGR of 10%, is a key player in the European Assembly Trays market. The country's strong automotive and industrial sectors drive demand for high-quality assembly trays. Germany's focus on innovation and sustainability aligns with the growing trend towards eco-friendly packaging solutions. However, the market faces challenges related to stringent regulatory requirements and the need for continuous innovation to maintain competitiveness.
India, with a market size of $1 billion and a CAGR of 20%, represents a rapidly growing market for assembly trays. The country's expanding manufacturing sector and government initiatives to promote domestic production are key growth drivers. Additionally, India's focus on improving infrastructure and logistics capabilities supports market expansion. However, challenges related to supply chain inefficiencies and regulatory compliance can hinder growth prospects.
Brazil, with a market size of $800 million and a CAGR of 15%, is a notable player in the Latin American Assembly Trays market. The country's growing automotive and electronics industries drive demand for assembly trays. Brazil's government policies aimed at promoting industrial growth and reducing import dependency further support market expansion. However, economic volatility and regulatory challenges can pose risks to market growth.
Assembly Trays Market Segments Insights

Product Type Analysis
The Assembly Trays market is segmented by product type into plastic assembly trays, metal trays, ESD trays, and custom trays. Plastic assembly trays dominate the market due to their lightweight nature, cost-effectiveness, and versatility. They are widely used across various industries, including electronics and automotive, where they provide reliable protection and organization for components. Metal trays, on the other hand, are favored for their durability and strength, making them ideal for heavy-duty applications. ESD trays are specifically designed to protect sensitive electronic components from electrostatic discharge, a critical requirement in the electronics industry. Custom trays offer tailored solutions to meet specific customer needs, providing a competitive advantage in a market where customization is increasingly valued.
Trends in the product type segment include the growing demand for sustainable and eco-friendly tray options. As environmental concerns continue to rise, manufacturers are exploring alternative materials and production methods to reduce their carbon footprint. Additionally, the increasing adoption of automation and robotics in manufacturing processes is driving demand for precision-engineered trays that can support automated assembly lines. Companies that can provide innovative and sustainable solutions are likely to gain a competitive edge in the market.
Material Type Analysis
The Assembly Trays market is also segmented by material type, including PP, ABS, stainless steel, and conductive polymers. PP (polypropylene) is the most commonly used material due to its lightweight, cost-effectiveness, and chemical resistance. It is widely used in the production of plastic assembly trays, which are favored for their versatility and ease of customization. ABS (acrylonitrile butadiene styrene) is another popular material, known for its strength and impact resistance, making it ideal for applications requiring durability and protection.
Stainless steel is favored for its strength and corrosion resistance, making it suitable for heavy-duty applications and environments where hygiene is a priority, such as in the medical and food industries. Conductive polymers are used in the production of ESD trays, providing protection against electrostatic discharge for sensitive electronic components. The material type segment is characterized by ongoing innovation and development, with manufacturers exploring new materials and composites to enhance performance and sustainability. As the market continues to evolve, companies that can offer a diverse range of material options to meet specific customer needs are likely to succeed.
Application Analysis
The Assembly Trays market is segmented by application into electronics assembly, automotive parts, medical devices, and industrial components. Electronics assembly is the largest application segment, driven by the growing demand for consumer electronics and the increasing complexity of electronic components. Assembly trays play a critical role in organizing and protecting components during the manufacturing process, ensuring efficiency and reliability.
The automotive parts segment is also a significant contributor to market growth, as manufacturers seek to optimize production processes and ensure the safe transport of components. The medical devices segment is characterized by stringent regulatory requirements and the need for high-quality, hygienic tray solutions. Industrial components represent a diverse range of applications, with demand driven by the need for durable and reliable packaging solutions in various manufacturing environments. As industries continue to evolve and innovate, the demand for specialized and customized tray solutions is expected to rise, presenting significant growth opportunities for market players.
End Use Analysis
The Assembly Trays market is segmented by end use into OEMs, contract manufacturers, workshops, and warehouses. OEMs (original equipment manufacturers) represent the largest end-use segment, as they require high-quality tray solutions to support their production processes and ensure the safe transport of components. Contract manufacturers also represent a significant market segment, as they provide outsourced manufacturing services to various industries and require reliable packaging solutions to meet their clients' needs.
Workshops and warehouses represent smaller but important segments, as they require durable and versatile tray solutions to support their operations. The end-use segment is characterized by a diverse range of customer needs and requirements, with demand driven by the need for efficient and reliable packaging solutions across various industries. As the market continues to evolve, companies that can offer tailored solutions to meet the specific needs of different end-use segments are likely to gain a competitive edge.
Assembly Trays Market Segments
The Assembly Trays market has been segmented on the basis ofProduct Type
- Plastic Assembly Trays
- Metal Trays
- ESD Trays
- Custom Trays
Material Type
- PP
- ABS
- Stainless Steel
- Conductive Polymers
Application
- Electronics Assembly
- Automotive Parts
- Medical Devices
- Industrial Components
End Use
- OEMs
- Contract Manufacturers
- Workshops
- Warehouses
Region
- Asia Pacific
- North America
- Latin America
- Europe
- Middle East & Africa