Retort Film Packaging Market Outlook
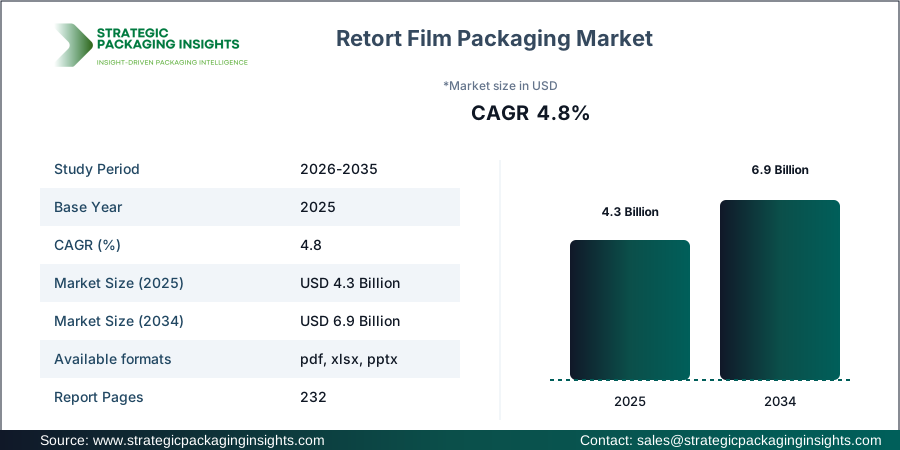
The Retort Film Packaging market size was valued at USD $4.3 Billion in 2025 and is anticipated to reach USD $6.9 Billion by 2035, growing at a CAGR of 4.8% % during the forecast period according to Strategic Packaging Insights. The increasing demand for convenient and shelf-stable food products is a significant driver for the market. The rise in urbanization and busy lifestyles has led to a surge in demand for ready-to-eat meals, soups, and sauces, which are major applications of retort film packaging.Report Scope
| Attributes | Details |
| Report Title | Retort Film Packaging Market Projected to Scale to 6.9 Billion by 2035, Assesses Strategic Packaging Insights |
| By Film Material | Polypropylene (PP), Polyethylene (PE), Polyethylene Terephthalate (PET), Polyamide (PA), Aluminum Foil, Ethylene Vinyl Alcohol (EVOH), Other Materials |
| By Film Structure | Three-Layer Films, Four-Layer Films, Five-Layer Films, Multi-Layer Films |
| By Film Type | Retortable CPP Films, Retortable PET Films, Retortable PA Films, High Barrier Retort Films, Transparent Retort Films, Metalized Retort Films |
| By Thickness | Below 50 Microns, 50–75 Microns, 76–100 Microns, Above 100 Microns |
| By Barrier Type | Oxygen Barrier, Moisture Barrier, Light Barrier, Aroma Barrier, High Barrier |
| By Application | Ready-to-Eat Meals, Soups and Sauces, Meat and Poultry, Seafood, Pet Food, Baby Food, Rice and Grains, Fruits and Vegetables, Other Food Products |
| By End Use Industry | Food and Beverage, Pet Food, Military and Defense, Foodservice, Healthcare, Other Industries |
| By Packaging Format | Retort Pouches, Retort Bags, Retort Trays, Retort Sachets, Lidding Films, Other Formats |
| By Region | North America, Europe, Asia-Pacific, Latin America, Middle East and Africa |
| Base Year | 2025 |
| Historic Period | 2018-2024 |
| Forecast Period | 2026-2035 |
| Number of Pages | 232 |
| Customization Available | Yes* |
Market Trends Analysis
Retort Film Packaging is witnessing a shift towards sustainable materials, with a focus on recyclability and reduced environmental impact. The adoption of mono-material films is gaining traction as companies aim to meet stringent sustainability goals. This trend is influencing procurement strategies and driving innovation in material science to enhance barrier properties while maintaining recyclability. Additionally, the integration of digital printing technologies is enabling customization and improving brand differentiation, which is crucial in a competitive market.
The market is also experiencing a rise in demand for high-barrier films that offer extended shelf life and protection against oxygen and moisture. This demand is particularly strong in the food and beverage sector, where maintaining product freshness is critical. The development of advanced multi-layer films with enhanced barrier properties is a key focus area for manufacturers, as they seek to cater to the evolving needs of consumers and regulatory requirements.
Industry Transformation Analysis
The Retort Film Packaging industry is undergoing significant transformation driven by technological advancements and sustainability imperatives. Manufacturers are investing in new extrusion and lamination technologies to improve operational efficiency and reduce waste. The shift towards localized production is also evident, as companies aim to minimize supply chain disruptions and reduce carbon footprints. This localization trend is supported by advancements in digital printing and automation, which enable flexible and cost-effective production.
Furthermore, the industry is witnessing consolidation as companies seek to enhance their competitive position through mergers and acquisitions. This consolidation is leading to increased capacity and technological capabilities, enabling companies to offer a broader range of products and services. The focus on sustainability is also driving changes in business models, with companies exploring circular economy initiatives and partnerships to enhance recycling and material recovery.
Trends & Disruptions Impacting Customers' Customers
Downstream customers, particularly in the food and beverage industry, are increasingly prioritizing sustainability and convenience. The demand for eco-friendly packaging solutions is rising, driven by consumer awareness and regulatory pressures. This shift is prompting brand owners to seek packaging solutions that offer recyclability and reduced environmental impact, influencing the demand for retort film packaging. Additionally, the growing trend of online food delivery and e-commerce is driving the need for durable and protective packaging that ensures product integrity during transit.
These changes are influencing product demand and innovation in the retort film packaging market. Companies are focusing on developing high-performance films that meet the evolving needs of their customers' customers. The emphasis on sustainability is also leading to increased collaboration between packaging manufacturers and brand owners to develop solutions that align with circular economy principles. This collaboration is creating new market opportunities and driving the adoption of advanced materials and technologies.
Retort Film Packaging Market Ecosystem
The Retort Film Packaging market ecosystem involves a complex interplay of raw material suppliers, film producers, converters, and end-users. The procurement of high-quality polymers and additives is critical for producing films with the desired barrier properties. Film production involves advanced extrusion and lamination processes to create multi-layer structures that offer superior protection and shelf life. Converters play a vital role in transforming films into various packaging formats, catering to diverse applications in the food and beverage industry.
Printing and lamination add value by enhancing the aesthetic appeal and functionality of the packaging. The distribution network ensures timely delivery of finished products to end-users, while recycling initiatives focus on recovering materials and minimizing environmental impact. The ecosystem's efficiency is influenced by supply chain dependencies, capacity constraints, and downstream demand, which collectively shape the market dynamics and growth opportunities.
Analyst Perspective
Analyst Perspective: The Retort Film Packaging market is poised for significant growth driven by the increasing demand for convenient and sustainable packaging solutions.
The shift towards mono-material films and high-barrier technologies is reshaping the competitive landscape, offering opportunities for innovation and differentiation. Companies that invest in advanced material science and digital printing technologies are likely to gain a competitive edge.
Market participants should closely monitor regulatory developments and consumer preferences, as these factors will influence procurement strategies and product development. The focus on sustainability and circular economy initiatives will be crucial for long-term success in this evolving market.
Opportunities & Threats
The Retort Film Packaging market presents significant opportunities driven by the growing demand for ready-to-eat meals and convenience foods. The increasing consumer preference for sustainable packaging solutions is encouraging manufacturers to develop eco-friendly films with enhanced recyclability. This trend is opening new avenues for product innovation and differentiation, particularly in the food and beverage sector.
Technological advancements in film production and barrier technologies are creating opportunities for companies to offer high-performance packaging solutions that meet the evolving needs of consumers and regulatory requirements. The integration of digital printing technologies is also enabling customization and improving brand differentiation, which is crucial in a competitive market.
However, the market faces threats from raw material price volatility and supply chain disruptions. The reliance on specific polymers and additives can lead to cost fluctuations, impacting profitability. Additionally, regulatory uncertainties related to packaging waste and recyclability pose challenges for manufacturers, requiring them to adapt to changing compliance requirements.
Competition from alternative packaging solutions and the need for significant capital investment in advanced production technologies are other challenges that companies must navigate. The focus on sustainability and circular economy initiatives will be crucial for long-term success in this evolving market.
Drivers & Challenges
The Retort Film Packaging market is driven by the increasing demand for convenient and shelf-stable food products. The rise in urbanization and busy lifestyles has led to a surge in demand for ready-to-eat meals, soups, and sauces, which are major applications of retort film packaging. Additionally, the growing awareness of food safety and hygiene is driving the adoption of high-barrier films that offer extended shelf life and protection against oxygen and moisture.
The focus on sustainability is another key driver, with companies investing in eco-friendly materials and technologies to meet consumer and regulatory expectations. The shift towards mono-material films and recyclable solutions is gaining traction, influencing procurement strategies and driving innovation in material science.
However, the market faces challenges related to raw material price volatility and supply chain disruptions. The reliance on specific polymers and additives can lead to cost fluctuations, impacting profitability. Additionally, regulatory uncertainties related to packaging waste and recyclability pose challenges for manufacturers, requiring them to adapt to changing compliance requirements.
Packaging Market Economics
The economics of Retort Film Packaging are influenced by raw material costs, conversion expenses, and energy consumption. The pricing of polymers such as polypropylene, polyethylene, and PET plays a significant role in determining the overall cost structure. Conversion costs, including extrusion and lamination, are critical factors that impact profitability. Energy costs also contribute to the overall expenses, particularly in film production and processing.
Printing and lamination add value to the packaging by enhancing its aesthetic appeal and functionality. Tooling and scrap management are essential considerations for optimizing production efficiency and minimizing waste. Logistics and distribution costs are influenced by the complexity of the supply chain and the need for timely delivery of finished products to end-users.
Packaging Value Chain & Cost Analysis
The value chain for Retort Film Packaging involves multiple tiers, from resin synthesis and film extrusion to converting and distribution. Tier-3 activities include resin synthesis, additives, and masterbatch production, which are critical for ensuring the quality and performance of the films. Tier-2 involves film extrusion and substrate production, where advanced technologies are employed to create multi-layer structures with superior barrier properties.
Tier-1 encompasses converting, printing, and lamination, where films are processed into various packaging formats and enhanced with graphics and additional layers. Downstream activities include co-packing, CPG brand filling, and distribution, ensuring that finished products reach end-users efficiently. The value chain is influenced by substrate lead times, capacity utilization, and resin supply, which collectively impact the market dynamics and growth opportunities.
Unit Economics & Substrate Cost Analysis
The unit economics of Retort Film Packaging are shaped by raw material costs, energy consumption, and conversion expenses. The pricing of polymers such as polypropylene, polyethylene, and PET is a significant factor in determining the overall cost structure. Energy costs, particularly in film production and processing, contribute to the overall expenses. Conversion costs, including extrusion and lamination, are critical factors that impact profitability.
Printing and lamination add value to the packaging by enhancing its aesthetic appeal and functionality. Tooling and scrap management are essential considerations for optimizing production efficiency and minimizing waste. Logistics and distribution costs are influenced by the complexity of the supply chain and the need for timely delivery of finished products to end-users.
Packaging Regulatory & Sustainability Analysis
The Retort Film Packaging market is subject to various regulatory requirements and sustainability initiatives. In the European Union, the Packaging and Packaging Waste Directive (PPWD) sets targets for recycling and waste reduction, influencing the development of eco-friendly packaging solutions. The U.S. Food and Drug Administration (FDA) regulates food-contact materials, ensuring the safety and compliance of retort films used in food packaging.
Sustainability is a key focus area, with companies investing in recyclable materials and technologies to meet consumer and regulatory expectations. The shift towards mono-material films and circular economy initiatives is gaining traction, driving innovation in material science and influencing procurement strategies. The emphasis on sustainability is also leading to increased collaboration between packaging manufacturers and brand owners to develop solutions that align with circular economy principles.
Strategic Mergers, Acquisitions & Capacity Expansions
Recent strategic developments in the Retort Film Packaging market include mergers and acquisitions aimed at enhancing technological capabilities and expanding market presence. Companies are investing in new production facilities and capacity expansions to meet the growing demand for high-performance films. For instance, Amcor plc has announced plans to expand its production capacity in Asia Pacific, focusing on sustainable packaging solutions.
Partnerships and collaborations are also on the rise, with companies seeking to leverage complementary strengths and technologies. The focus on sustainability is driving investments in recycling facilities and circular economy initiatives, enabling companies to offer eco-friendly packaging solutions. These strategic developments are reshaping the competitive landscape and creating new opportunities for growth and innovation.
Strategic Action Directives
Brand Packaging Engineers & Sustainability Directors should prioritize material selection and recyclability to meet consumer and regulatory expectations. The focus on mono-material qualification and barrier performance is crucial for developing sustainable packaging solutions.
Converter Operations & Extrusion Leads should optimize line speed and tooling to enhance production efficiency and reduce scrap. The integration of advanced technologies and automation can improve capacity utilization and product quality.
Procurement & Material Sourcing Managers should focus on resin contracts and price indexing to manage cost fluctuations. Supplier diversification and EPR exposure are critical considerations for ensuring a stable supply chain.
Investors should monitor capacity expansions and technological advancements to identify growth opportunities. The focus on sustainability and circular economy initiatives will be crucial for long-term success in this evolving market.
Market Share Analysis
The Retort Film Packaging market is characterized by a competitive landscape with several key players vying for market share. Companies such as Amcor plc, Mondi Group, and ProAmpac are prominent players, leveraging their technological capabilities and extensive product portfolios to maintain a strong market position. These companies are focusing on innovation and sustainability to differentiate themselves in a competitive market.
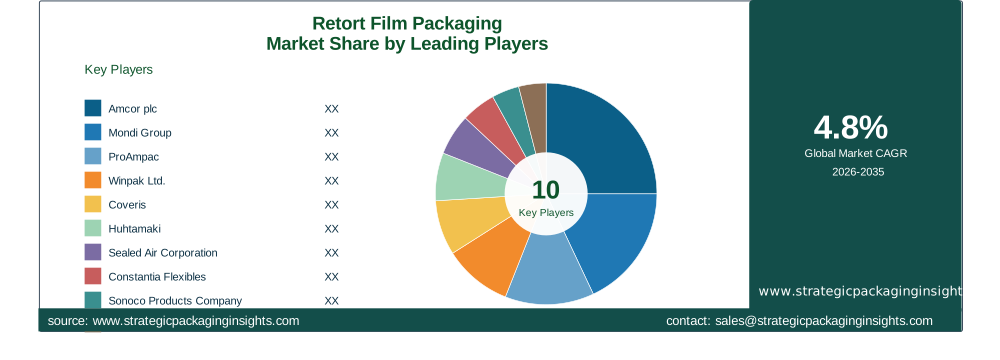
Amcor plc is a leading player in the market, known for its advanced packaging solutions and commitment to sustainability. The company has a strong presence in Asia Pacific and North America, where it is investing in capacity expansions and new technologies to meet the growing demand for eco-friendly packaging solutions.
Mondi Group is another key player, offering a wide range of retort film packaging solutions for various applications. The company is focusing on product innovation and sustainability, with a strong emphasis on recyclability and reduced environmental impact. Mondi Group has a significant presence in Europe and is expanding its operations in emerging markets.
ProAmpac is a major player in the retort film packaging market, known for its high-performance films and commitment to sustainability. The company is investing in new production facilities and capacity expansions to meet the growing demand for advanced packaging solutions. ProAmpac has a strong presence in North America and is expanding its operations in Asia Pacific.
Key Highlights
- Largest Region: North America
- Fastest-Growing Region: Asia Pacific
- Largest Segment: Food and Beverage
- Fastest-Growing Segment: High Barrier Retort Films
- Base-year market size: $4.3 Billion
- Forecast-year market size: $6.9 Billion
- CAGR: 4.8%
- Important application: Ready-to-Eat Meals
- Major end-use industry: Food and Beverage
- Major market driver: Demand for convenient and shelf-stable food products
Regional Insights
The Retort Film Packaging market is witnessing significant growth across major regions, with North America being the largest market due to the high demand for convenient and shelf-stable food products. Asia Pacific is the fastest-growing region, driven by rapid urbanization and increasing consumer preference for ready-to-eat meals.
North America
North America is the largest market for Retort Film Packaging, driven by the high demand for convenient and shelf-stable food products. The region is characterized by a strong presence of key players and advanced packaging technologies. The focus on sustainability and recyclability is influencing product development and procurement strategies.
The U.S. is a major contributor to the market, with a high demand for ready-to-eat meals and convenience foods. The emphasis on food safety and hygiene is driving the adoption of high-barrier films that offer extended shelf life and protection against oxygen and moisture.
Europe
Europe is a significant market for Retort Film Packaging, with a strong emphasis on sustainability and recyclability. The region is characterized by stringent regulatory requirements and a focus on eco-friendly packaging solutions. The demand for high-barrier films is driven by the need for extended shelf life and product protection.
Germany and the U.K. are major contributors to the market, with a high demand for ready-to-eat meals and convenience foods. The focus on sustainability is driving innovation in material science and influencing procurement strategies.
Asia Pacific
Asia Pacific is the fastest-growing region for Retort Film Packaging, driven by rapid urbanization and increasing consumer preference for ready-to-eat meals. The region is characterized by a strong presence of key players and advanced packaging technologies. The focus on sustainability and recyclability is influencing product development and procurement strategies.
China and India are major contributors to the market, with a high demand for convenience foods and ready-to-eat meals. The emphasis on food safety and hygiene is driving the adoption of high-barrier films that offer extended shelf life and protection against oxygen and moisture.
Latin America
Latin America is a growing market for Retort Film Packaging, driven by the increasing demand for convenience foods and ready-to-eat meals. The region is characterized by a strong presence of key players and advanced packaging technologies. The focus on sustainability and recyclability is influencing product development and procurement strategies.
Brazil and Mexico are major contributors to the market, with a high demand for convenience foods and ready-to-eat meals. The emphasis on food safety and hygiene is driving the adoption of high-barrier films that offer extended shelf life and protection against oxygen and moisture.
Middle East & Africa
The Middle East & Africa is a growing market for Retort Film Packaging, driven by the increasing demand for convenience foods and ready-to-eat meals. The region is characterized by a strong presence of key players and advanced packaging technologies. The focus on sustainability and recyclability is influencing product development and procurement strategies.
South Africa and the UAE are major contributors to the market, with a high demand for convenience foods and ready-to-eat meals. The emphasis on food safety and hygiene is driving the adoption of high-barrier films that offer extended shelf life and protection against oxygen and moisture.
Retort Film Packaging Market Segments Insights

By Film Material Analysis
The Retort Film Packaging market is segmented by film material, with polypropylene (PP) and polyethylene (PE) being the most widely used materials due to their excellent barrier properties and cost-effectiveness. Polyethylene Terephthalate (PET) is also gaining popularity for its high strength and clarity, making it suitable for transparent retort films. The demand for aluminum foil is driven by its superior barrier properties, while Ethylene Vinyl Alcohol (EVOH) is used for its excellent oxygen barrier capabilities.
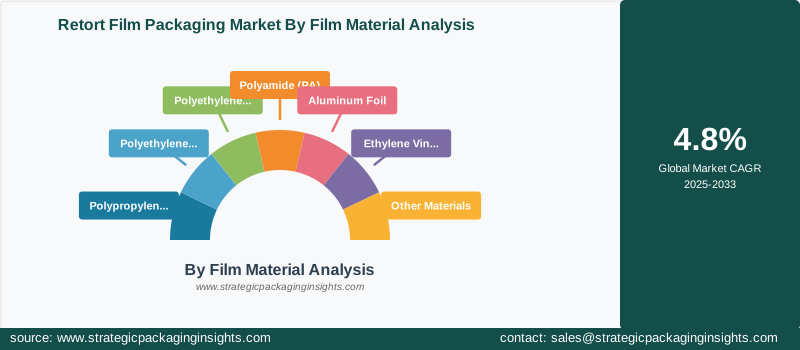
The choice of film material is influenced by factors such as cost, barrier requirements, and recyclability. Manufacturers are focusing on developing eco-friendly materials that offer enhanced recyclability and reduced environmental impact. The shift towards mono-material films is gaining traction, driven by the need for sustainable packaging solutions that meet regulatory requirements and consumer expectations.
By Film Structure Analysis
The market is segmented by film structure, with multi-layer films being the most popular choice due to their superior barrier properties and versatility. Three-layer films are commonly used for applications that require moderate barrier protection, while four-layer and five-layer films offer enhanced protection against oxygen, moisture, and light. The demand for multi-layer films is driven by the need for extended shelf life and product protection, particularly in the food and beverage industry.
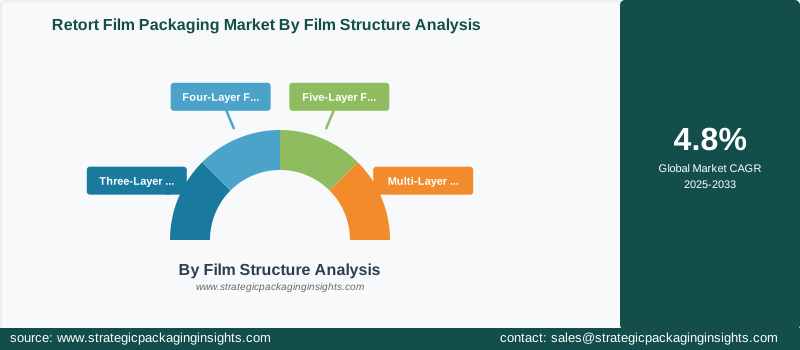
Manufacturers are focusing on developing advanced multi-layer films that offer high barrier performance while maintaining recyclability. The integration of new materials and technologies is enabling the production of films with improved barrier properties and reduced environmental impact. The shift towards sustainable packaging solutions is influencing the choice of film structure, with companies exploring new combinations of materials to meet evolving consumer and regulatory requirements.
By Film Type Analysis
The Retort Film Packaging market is segmented by film type, with retortable CPP films and retortable PET films being the most widely used due to their excellent barrier properties and cost-effectiveness. High barrier retort films are gaining popularity for their ability to offer extended shelf life and protection against oxygen and moisture. Transparent retort films are preferred for applications that require product visibility, while metalized retort films offer enhanced barrier protection and aesthetic appeal.
The choice of film type is influenced by factors such as barrier requirements, cost, and recyclability. Manufacturers are focusing on developing high-performance films that meet the evolving needs of consumers and regulatory requirements. The shift towards sustainable packaging solutions is driving innovation in material science and influencing the choice of film type, with companies exploring new combinations of materials to enhance barrier performance and recyclability.
By Thickness Analysis
The market is segmented by thickness, with films below 50 microns being the most widely used due to their cost-effectiveness and versatility. Films with a thickness of 50-75 microns offer enhanced barrier protection and are commonly used for applications that require moderate protection against oxygen and moisture. Films with a thickness of 76-100 microns and above 100 microns are preferred for applications that require high barrier performance and extended shelf life.
The choice of film thickness is influenced by factors such as barrier requirements, cost, and recyclability. Manufacturers are focusing on developing films with optimized thickness that offer high barrier performance while maintaining cost-effectiveness and recyclability. The shift towards sustainable packaging solutions is driving innovation in material science and influencing the choice of film thickness, with companies exploring new combinations of materials to enhance barrier performance and recyclability.
By Barrier Type Analysis
The Retort Film Packaging market is segmented by barrier type, with oxygen barrier films being the most widely used due to their ability to offer extended shelf life and protection against oxygen. Moisture barrier films are also popular for their ability to protect against moisture and maintain product freshness. Light barrier films are preferred for applications that require protection against light, while aroma barrier films are used for applications that require protection against aroma loss.
The choice of barrier type is influenced by factors such as barrier requirements, cost, and recyclability. Manufacturers are focusing on developing high-performance films that meet the evolving needs of consumers and regulatory requirements. The shift towards sustainable packaging solutions is driving innovation in material science and influencing the choice of barrier type, with companies exploring new combinations of materials to enhance barrier performance and recyclability.
By Application Analysis
The Retort Film Packaging market is segmented by application, with ready-to-eat meals being the most widely used due to their convenience and shelf-stability. Soups and sauces are also popular for their ability to offer extended shelf life and protection against oxygen and moisture. Meat and poultry, seafood, and pet food are other major applications, driven by the need for high barrier performance and extended shelf life.
The choice of application is influenced by factors such as barrier requirements, cost, and recyclability. Manufacturers are focusing on developing high-performance films that meet the evolving needs of consumers and regulatory requirements. The shift towards sustainable packaging solutions is driving innovation in material science and influencing the choice of application, with companies exploring new combinations of materials to enhance barrier performance and recyclability.
By End Use Industry Analysis
The Retort Film Packaging market is segmented by end use industry, with the food and beverage industry being the most widely used due to its high demand for convenient and shelf-stable food products. The pet food industry is also popular for its ability to offer extended shelf life and protection against oxygen and moisture. The military and defense, foodservice, and healthcare industries are other major end use industries, driven by the need for high barrier performance and extended shelf life.
The choice of end use industry is influenced by factors such as barrier requirements, cost, and recyclability. Manufacturers are focusing on developing high-performance films that meet the evolving needs of consumers and regulatory requirements. The shift towards sustainable packaging solutions is driving innovation in material science and influencing the choice of end use industry, with companies exploring new combinations of materials to enhance barrier performance and recyclability.
By Packaging Format Analysis
The Retort Film Packaging market is segmented by packaging format, with retort pouches being the most widely used due to their convenience and shelf-stability. Retort bags and retort trays are also popular for their ability to offer extended shelf life and protection against oxygen and moisture. Retort sachets, lidding films, and other formats are other major packaging formats, driven by the need for high barrier performance and extended shelf life.
The choice of packaging format is influenced by factors such as barrier requirements, cost, and recyclability. Manufacturers are focusing on developing high-performance films that meet the evolving needs of consumers and regulatory requirements. The shift towards sustainable packaging solutions is driving innovation in material science and influencing the choice of packaging format, with companies exploring new combinations of materials to enhance barrier performance and recyclability.
Retort Film Packaging Market Segments
The Retort Film Packaging market has been segmented on the basis ofBy Film Material
- Polypropylene (PP)
- Polyethylene (PE)
- Polyethylene Terephthalate (PET)
- Polyamide (PA)
- Aluminum Foil
- Ethylene Vinyl Alcohol (EVOH)
- Other Materials
By Film Structure
- Three-Layer Films
- Four-Layer Films
- Five-Layer Films
- Multi-Layer Films
By Film Type
- Retortable CPP Films
- Retortable PET Films
- Retortable PA Films
- High Barrier Retort Films
- Transparent Retort Films
- Metalized Retort Films
By Thickness
- Below 50 Microns
- 50–75 Microns
- 76–100 Microns
- Above 100 Microns
By Barrier Type
- Oxygen Barrier
- Moisture Barrier
- Light Barrier
- Aroma Barrier
- High Barrier
By Application
- Ready-to-Eat Meals
- Soups and Sauces
- Meat and Poultry
- Seafood
- Pet Food
- Baby Food
- Rice and Grains
- Fruits and Vegetables
- Other Food Products
By End Use Industry
- Food and Beverage
- Pet Food
- Military and Defense
- Foodservice
- Healthcare
- Other Industries
By Packaging Format
- Retort Pouches
- Retort Bags
- Retort Trays
- Retort Sachets
- Lidding Films
- Other Formats
By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East and Africa