PVDC Coated Films Market Outlook
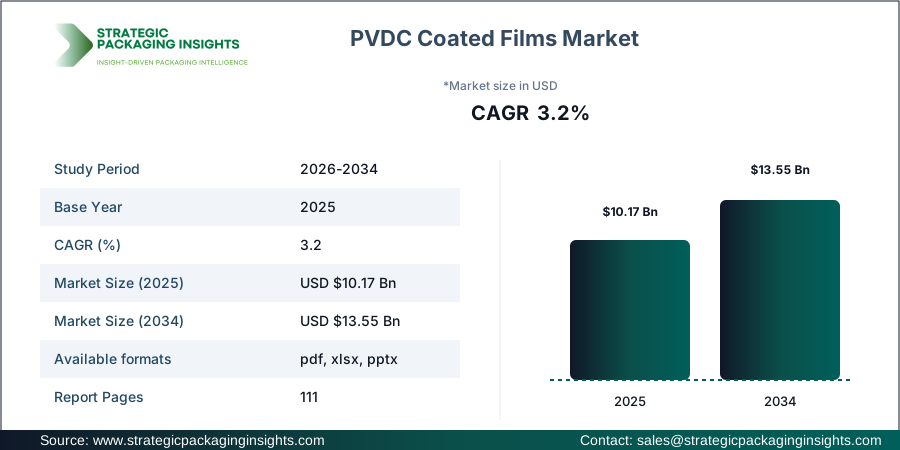
The PVDC Coated Films market size was valued at USD 10.17 billion in 2025 and is anticipated to reach USD 13.55 billion by 2034, growing at a CAGR of 3.2% during the forecast period according to Strategic Packaging Insights. The market is driven by the increasing demand for high-barrier packaging solutions in the food and pharmaceutical industries. Companies like Klöckner Pentaplast and Cosmo First are at the forefront, leveraging advanced coating technologies to enhance the barrier properties of PVDC films. The growing consumer preference for packaged food products, coupled with the need for extended shelf life, is propelling the demand for PVDC coated films. Additionally, the healthcare sector's reliance on PVDC films for pharma blister packaging is further boosting market growth.
One of the most impactful drivers of the PVDC Coated Films market is the stringent regulations on food safety and pharmaceutical packaging. Governments worldwide are enforcing regulations that mandate the use of high-barrier materials to prevent contamination and ensure product integrity. This regulatory push is encouraging manufacturers to adopt PVDC coated films, known for their excellent barrier properties against oxygen, moisture, and aroma. Companies like UFlex and Jindal Poly Films are investing in research and development to innovate and comply with these regulations, thereby enhancing their market position. The increasing awareness about food safety and quality among consumers is also driving the demand for PVDC coated films, making it a lucrative market for investors and stakeholders.
Report Scope
| Attributes | Details |
| Report Title | PVDC Coated Films Market Size, Future Growth and Forecast 2034 |
| By Substrate Type | BOPP, PET, PVC, Paper |
| By Application | Food Packaging, Pharma Blisters, Meat Packaging, Dairy Packaging |
| By End Use | Food & Beverage, Healthcare, FMCG, Packaging Converters |
| By Barrier Type | Oxygen Barrier, Moisture Barrier, Aroma Barrier |
| Region | Asia Pacific, North America, Latin America, Europe, Middle East & Africa |
| Base Year | 2025 |
| Historic Period | 2018-2024 |
| Forecast Period | 2026-2034 |
| Number of Pages | 111 |
| Customization Available | Yes* |
Sustainability & Circular Economy Analysis
Sustainability initiatives and circular economy practices are significantly influencing the PVDC Coated Films market. As environmental concerns rise, there is a growing emphasis on using recyclable materials and developing eco-friendly packaging solutions. Companies are investing in research to create PVDC films that are not only effective in barrier protection but also environmentally sustainable. This shift towards sustainability is driving innovation in packaging design, with a focus on reducing material usage and enhancing recyclability. The integration of lightweight packaging solutions is also gaining traction, as it reduces transportation costs and carbon emissions, aligning with global sustainability goals.
Moreover, extended producer responsibility (EPR) regulations are pushing manufacturers to take accountability for the entire lifecycle of their products, including disposal and recycling. This has led to the development of waste reduction strategies and the adoption of eco-friendly material innovations in the PVDC Coated Films market. Companies like Mondi and Amcor are leading the charge by implementing ESG initiatives that focus on reducing their carbon footprint and promoting sustainable practices across their supply chains. These efforts not only enhance brand reputation but also ensure compliance with stringent packaging regulations, thereby maintaining long-term market competitiveness.
Consumer preferences are also shifting towards sustainable packaging solutions, influencing investment decisions and supply chain strategies. The demand for packaging that aligns with environmental values is prompting companies to rethink their manufacturing processes and material sourcing. By adopting circular economy practices, such as recycling networks and reusable packaging, companies can meet consumer expectations while achieving cost efficiencies. This trend is expected to continue shaping the PVDC Coated Films market, as stakeholders prioritize sustainability to gain a competitive edge and ensure regulatory compliance.
Packaging Value Chain & Supply Chain Analysis
The packaging value chain for PVDC Coated Films involves a complex ecosystem of raw material suppliers, converters, manufacturers, and logistics providers. Raw material sourcing is critical, as the availability and cost of PVDC resin directly impact production capabilities and pricing strategies. Packaging converters play a vital role in transforming raw materials into finished films, with companies like Innovia Films and Toray Industries leading in technological advancements. Efficient procurement strategies and inventory management are essential to maintaining supply chain resilience and ensuring timely delivery to brand owners and retailers.
Supply chain efficiency is further influenced by transportation and logistics, which are crucial for distributing PVDC coated films to various end-use industries. Strategic partnerships with logistics providers enable manufacturers to optimize distribution channels and reduce lead times. Localization of production facilities is also becoming a key strategy to mitigate risks associated with global sourcing and enhance supply chain agility. Companies are investing in advanced packaging machinery to improve production efficiency and meet the growing demand for high-barrier films in the food and healthcare sectors.
Recycling networks are an integral part of the PVDC Coated Films supply chain, as they facilitate the collection and processing of used films for reuse. This not only supports sustainability goals but also reduces raw material dependency and production costs. Brand owners and retailers are increasingly collaborating with recycling partners to enhance their sustainability credentials and meet consumer expectations. The integration of circular economy practices into the supply chain is expected to drive long-term growth and competitiveness in the PVDC Coated Films market, as companies strive to balance cost efficiency with environmental responsibility.
Opportunities & Threats
The PVDC Coated Films market presents several opportunities for growth, driven by the increasing demand for high-barrier packaging solutions in emerging markets. The expansion of the food and beverage industry in regions like Asia Pacific and Latin America offers significant potential for market players. Companies can capitalize on this opportunity by developing innovative PVDC films that cater to the specific needs of these markets, such as enhanced moisture and aroma barriers. Additionally, the growing trend of online food delivery and e-commerce is boosting the demand for durable and protective packaging solutions, further driving the adoption of PVDC coated films.
Technological advancements in coating processes and material science present another opportunity for market growth. Companies that invest in research and development to enhance the performance and sustainability of PVDC films can gain a competitive edge. The development of bio-based PVDC films and the integration of smart packaging technologies are areas with significant growth potential. By leveraging these innovations, companies can meet the evolving demands of consumers and regulatory bodies, ensuring long-term success in the market.
However, the PVDC Coated Films market also faces certain threats, primarily from the increasing competition from alternative packaging materials. The rise of biodegradable and compostable films poses a challenge to PVDC films, as consumers and regulators push for more sustainable packaging solutions. Additionally, fluctuations in raw material prices and supply chain disruptions can impact production costs and profitability. Companies must navigate these challenges by diversifying their product portfolios and adopting flexible sourcing strategies to mitigate risks and maintain market share.
Drivers & Challenges
The primary driver of the PVDC Coated Films market is the growing demand for high-barrier packaging solutions in the food and pharmaceutical industries. The need for extended shelf life and protection against contamination is driving the adoption of PVDC films, known for their excellent barrier properties. Companies like Bilcare and Constantia Flexibles are leveraging advanced coating technologies to enhance the performance of PVDC films, meeting the stringent requirements of these industries. Additionally, the increasing consumer preference for packaged food products is fueling market growth, as PVDC films offer superior protection and preservation capabilities.
Another significant driver is the regulatory push for food safety and pharmaceutical packaging standards. Governments worldwide are implementing stringent regulations that mandate the use of high-barrier materials to ensure product integrity and consumer safety. This regulatory environment is encouraging manufacturers to adopt PVDC coated films, which comply with these standards and offer reliable protection against oxygen, moisture, and aroma. Companies are investing in research and development to innovate and meet these regulatory requirements, thereby enhancing their market position and competitiveness.
Despite these drivers, the PVDC Coated Films market faces challenges, particularly from the increasing competition from alternative packaging materials. The rise of biodegradable and compostable films is posing a threat to PVDC films, as consumers and regulators demand more sustainable packaging solutions. Additionally, fluctuations in raw material prices and supply chain disruptions can impact production costs and profitability. Companies must navigate these challenges by diversifying their product portfolios and adopting flexible sourcing strategies to mitigate risks and maintain market share.
Market Share Analysis
The PVDC Coated Films market is characterized by a competitive landscape with several key players vying for market share. Companies like Klöckner Pentaplast, Cosmo First, and UFlex are leading the market, leveraging their extensive product portfolios and technological expertise to maintain a competitive edge. These companies are focusing on expanding their production capacities and enhancing their distribution networks to meet the growing demand for PVDC coated films. Strategic partnerships and collaborations with end-use industries are also a common strategy among market leaders to strengthen their market position.
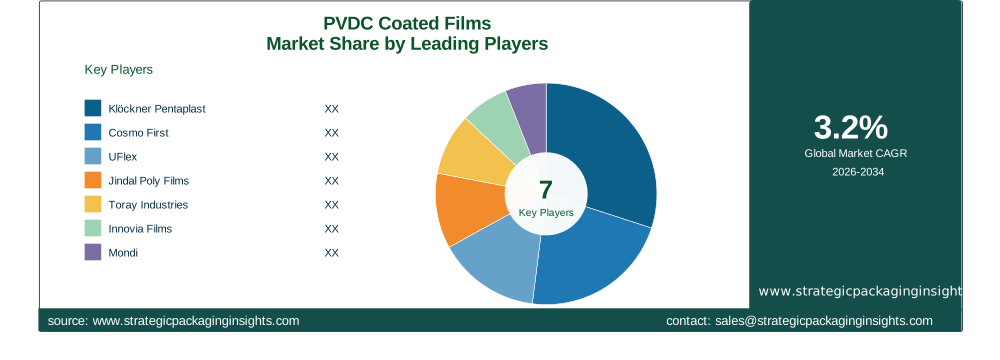
Klöckner Pentaplast is a prominent player in the PVDC Coated Films market, known for its innovative solutions and commitment to sustainability. The company offers a wide range of PVDC films that cater to various applications, including food packaging and pharmaceutical blisters. Cosmo First, another key player, is recognized for its advanced coating technologies and focus on product development. The company is investing in research and development to enhance the barrier properties of its PVDC films and meet the evolving demands of consumers and regulatory bodies.
UFlex is a leading manufacturer of PVDC coated films, with a strong presence in the global market. The company is known for its state-of-the-art manufacturing facilities and commitment to quality and sustainability. Jindal Poly Films is another major player, offering a diverse range of PVDC films for various end-use industries. The company is focusing on expanding its production capacities and enhancing its distribution networks to meet the growing demand for high-barrier packaging solutions.
Other notable players in the PVDC Coated Films market include Toray Industries, Innovia Films, Mondi, Amcor, Bilcare, and Constantia Flexibles. These companies are investing in research and development to innovate and enhance the performance of their PVDC films. Strategic partnerships and collaborations with end-use industries are also a common strategy among market leaders to strengthen their market position. The competitive landscape of the PVDC Coated Films market is expected to remain dynamic, with companies focusing on innovation and sustainability to gain a competitive edge.
Key Highlights
- Market Size: USD 10.17 billion in 2025, projected to reach USD 13.55 billion by 2034.
- Growth Rate: CAGR of 3.2% during the forecast period.
- Leading Companies: Klöckner Pentaplast, Cosmo First, UFlex, Jindal Poly Films.
- Key Applications: Food Packaging, Pharma Blisters, Meat Packaging, Dairy Packaging.
- Regional Growth: Significant growth expected in Asia Pacific and Latin America.
- Barrier Types: Oxygen Barrier, Moisture Barrier, Aroma Barrier.
- Sustainability Focus: Increasing emphasis on recyclable and eco-friendly materials.
PVDC Coated Films Market Segments Insights

By Substrate Type Analysis
The PVDC Coated Films market is segmented by substrate type, including BOPP, PET, PVC, and Paper. BOPP films are gaining popularity due to their excellent clarity and barrier properties, making them ideal for food packaging applications. Companies like Innovia Films and Toray Industries are focusing on enhancing the performance of BOPP films through advanced coating technologies. PET films, known for their durability and versatility, are widely used in pharmaceutical and dairy packaging. The demand for PVC films is driven by their cost-effectiveness and suitability for various applications, including meat packaging. Paper substrates are gaining traction as eco-friendly alternatives, aligning with the growing sustainability trend in the packaging industry.
Innovation in substrate materials is a key driver of growth in this segment. Companies are investing in research and development to create substrates that offer superior barrier properties while being environmentally sustainable. The integration of bio-based materials and recyclable substrates is a significant trend, as manufacturers strive to meet consumer demand for sustainable packaging solutions. The competitive landscape in this segment is characterized by technological advancements and strategic partnerships, as companies aim to enhance their product offerings and expand their market presence.
By Application Analysis
The application segment of the PVDC Coated Films market includes food packaging, pharma blisters, meat packaging, and dairy packaging. Food packaging is the largest application segment, driven by the increasing demand for packaged food products and the need for extended shelf life. PVDC films are preferred for their excellent barrier properties, which protect against moisture, oxygen, and aroma, ensuring product freshness and quality. The pharmaceutical industry relies on PVDC films for blister packaging, as they provide reliable protection against contamination and ensure product integrity.
Meat packaging is another significant application, with PVDC films offering superior barrier protection to prevent spoilage and extend shelf life. Dairy packaging is also witnessing growth, as PVDC films provide effective protection against moisture and oxygen, preserving the quality and freshness of dairy products. Companies are focusing on developing application-specific PVDC films that cater to the unique requirements of each industry, driving innovation and growth in this segment. The increasing consumer preference for packaged food and pharmaceutical products is expected to continue driving demand for PVDC coated films in these applications.
By End Use Analysis
The PVDC Coated Films market is segmented by end use, including food & beverage, healthcare, FMCG, and packaging converters. The food & beverage industry is the largest end-use segment, driven by the increasing demand for packaged food products and the need for high-barrier packaging solutions. PVDC films are preferred for their excellent barrier properties, which protect against moisture, oxygen, and aroma, ensuring product freshness and quality. The healthcare industry relies on PVDC films for pharmaceutical packaging, as they provide reliable protection against contamination and ensure product integrity.
The FMCG sector is also witnessing growth, as PVDC films offer effective protection for a wide range of consumer goods, including personal care and household products. Packaging converters play a crucial role in the value chain, transforming raw materials into finished films and catering to the specific needs of end-use industries. Companies are focusing on developing end-use-specific PVDC films that cater to the unique requirements of each industry, driving innovation and growth in this segment. The increasing consumer preference for packaged food and pharmaceutical products is expected to continue driving demand for PVDC coated films in these end-use applications.
By Barrier Type Analysis
The PVDC Coated Films market is segmented by barrier type, including oxygen barrier, moisture barrier, and aroma barrier. Oxygen barrier films are in high demand due to their ability to prevent oxidation and extend the shelf life of packaged products. Companies like Mondi and Amcor are focusing on enhancing the oxygen barrier properties of PVDC films through advanced coating technologies. Moisture barrier films are essential for protecting products from humidity and moisture, ensuring product quality and freshness. The demand for aroma barrier films is driven by the need to preserve the flavor and aroma of packaged food products.
Innovation in barrier technologies is a key driver of growth in this segment. Companies are investing in research and development to create films that offer superior barrier properties while being environmentally sustainable. The integration of bio-based materials and recyclable substrates is a significant trend, as manufacturers strive to meet consumer demand for sustainable packaging solutions. The competitive landscape in this segment is characterized by technological advancements and strategic partnerships, as companies aim to enhance their product offerings and expand their market presence.
PVDC Coated Films Market Segments
The PVDC Coated Films market has been segmented on the basis ofBy Substrate Type
- BOPP
- PET
- PVC
- Paper
By Application
- Food Packaging
- Pharma Blisters
- Meat Packaging
- Dairy Packaging
By End Use
- Food & Beverage
- Healthcare
- FMCG
- Packaging Converters
By Barrier Type
- Oxygen Barrier
- Moisture Barrier
- Aroma Barrier
Region
- Asia Pacific
- North America
- Latin America
- Europe
- Middle East & Africa