Flexible Lid Stock Packaging Market Outlook
The Flexible Lid Stock Packaging market size was valued at USD $8.7 Billion in 2025 and is anticipated to reach USD $13.9 Billion by 2035, growing at a CAGR of 4.8% during the forecast period according to Strategic Packaging Insights.
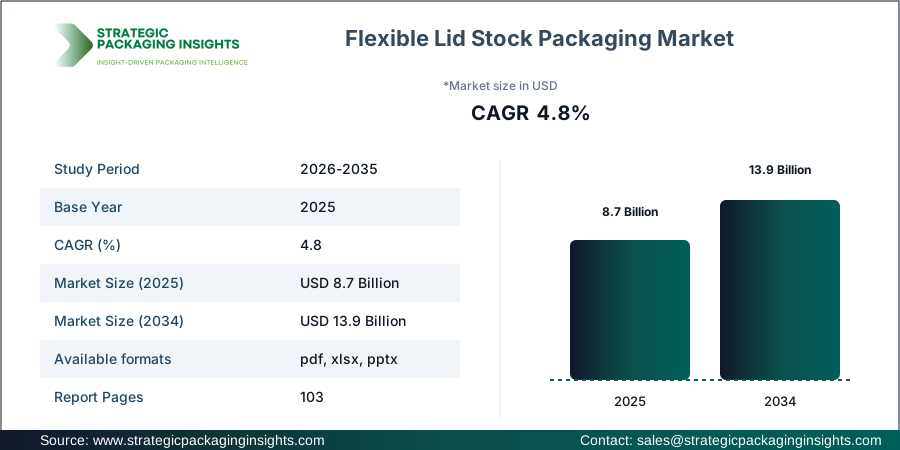
The increasing demand for convenience foods and ready-to-eat meals is a significant driver for the market. As consumers seek more convenient packaging solutions, the demand for flexible lid stock packaging, which offers ease of use and extended shelf life, is expected to rise. Additionally, the growing focus on sustainability and recyclability in packaging is pushing manufacturers to innovate with eco-friendly materials and technologies.
Report Scope
| Attributes | Details |
| Report Title | Flexible Lid Stock Packaging Market Projected to Scale to 13.9 Billion by 2035, Assesses Strategic Packaging Insights |
| By Material | Polyethylene (PE), Polypropylene (PP), Polyethylene Terephthalate (PET), Polyamide (PA), Aluminum Foil, Paper and Paperboard, Ethylene Vinyl Alcohol (EVOH), Multi-Layer Laminates |
| By Lid Type | Peelable Lids, Resealable Lids, Heat-Seal Lids, Easy-Open Lids, Die-Cut Lids, Pressure-Sensitive Lids |
| By Packaging Format | Cups, Trays, Tubs, Bowls, Containers, Pouches, Other Flexible Packaging Formats |
| By Barrier Property | High Oxygen Barrier, Moisture Barrier, Light Barrier, Aroma Barrier, Gas Barrier, Standard Barrier |
| By Application | Food Packaging, Dairy Products, Meat and Seafood, Ready-to-Eat Meals, Snacks, Pet Food, Pharmaceuticals, Medical Products, Personal Care Products |
| By Sealing Technology | Heat Sealing, Ultrasonic Sealing, Induction Sealing, Adhesive Sealing |
| By End Use Industry | Food and Beverage, Pharmaceuticals and Healthcare, Personal Care and Cosmetics, Pet Food, Household Products, Industrial Products |
| By Sustainability | Conventional Laminates, Recyclable Laminates, Mono-Material Films, Post-Consumer Recycled Materials, Bio-Based Materials, Compostable Materials |
| By Distribution Channel | Direct Sales, Packaging Distributors, Specialty Packaging Suppliers, Online Sales |
| By Region | North America, Europe, Asia-Pacific, Latin America, Middle East and Africa |
| Base Year | 2025 |
| Historic Period | 2018-2024 |
| Forecast Period | 2026-2035 |
| Number of Pages | 103 |
| Customization Available | Yes* |
Market Trends Analysis
One of the major trends in the Flexible Lid Stock Packaging market is the shift towards sustainable packaging solutions. Companies are increasingly adopting recyclable and bio-based materials to meet consumer demand for environmentally friendly products. This trend is driven by regulatory pressures and brand owners' sustainability commitments, which are influencing procurement and product development strategies.
Another significant trend is the advancement in sealing technologies, such as ultrasonic and induction sealing, which enhance the functionality and integrity of flexible lid stock packaging. These technologies are gaining traction due to their ability to provide superior sealing performance, reduce material usage, and improve operational efficiency. As a result, manufacturers are investing in these technologies to gain a competitive edge and meet the evolving needs of end-users.
Industry Transformation Analysis
The Flexible Lid Stock Packaging industry is undergoing a transformation with increased focus on automation and digitalization. Manufacturers are adopting advanced machinery and automation solutions to enhance production efficiency and reduce operational costs. This shift is driven by the need to meet growing demand while maintaining high-quality standards and minimizing waste.
Additionally, the industry is witnessing a shift towards localized production to reduce supply chain complexities and improve responsiveness to regional market demands. This trend is particularly evident in regions like Asia Pacific, where local manufacturing capabilities are being expanded to cater to the rising demand for flexible packaging solutions. As a result, companies are investing in capacity expansion and strategic partnerships to strengthen their market position.
Trends & Disruptions Impacting Customers' Customers
Downstream customers, particularly in the food and beverage industry, are increasingly prioritizing sustainability and convenience in their packaging choices. This shift is driven by changing consumer preferences towards eco-friendly and easy-to-use packaging solutions. As a result, companies are focusing on developing flexible lid stock packaging that meets these demands, incorporating features like resealability and recyclability.
The emphasis on sustainability and convenience is influencing product demand and innovation in the Flexible Lid Stock Packaging market. Companies are investing in research and development to create packaging solutions that align with these trends, leading to new market opportunities and growth potential. Additionally, suppliers are being required to meet stricter sustainability criteria, impacting procurement strategies and supplier relationships.
Flexible Lid Stock Packaging Market Ecosystem
The Flexible Lid Stock Packaging market ecosystem involves a complex interplay of raw material suppliers, converters, and distributors. Raw materials such as polymers, aluminum, and paperboard are procured from global suppliers and processed into films and sheets through extrusion and lamination. These materials are then converted into finished lid stock products through die-cutting and printing processes.
Distribution plays a crucial role in ensuring timely delivery of products to end-users, with logistics and supply chain management being key components. Additionally, recycling and end-of-life processing are becoming increasingly important as sustainability becomes a priority for both manufacturers and consumers. Companies are investing in recycling technologies and infrastructure to enhance the recyclability of flexible lid stock packaging and reduce environmental impact.
Analyst Perspective
Analyst Perspective: The Flexible Lid Stock Packaging market is poised for significant growth driven by sustainability and convenience trends. Companies are focusing on developing eco-friendly and user-friendly packaging solutions to meet evolving consumer demands.
The most important structural change is the shift towards sustainable materials and technologies, which is reshaping the competitive landscape. Companies that can innovate and adapt to these changes are likely to gain a competitive advantage and capture market share.
During the forecast period, companies, investors, and suppliers should closely monitor advancements in sustainable materials and sealing technologies. These developments are expected to drive market growth and create new opportunities for innovation and differentiation.
Opportunities & Threats
The Flexible Lid Stock Packaging market presents significant opportunities for growth, particularly in the area of sustainable packaging solutions. As consumers and regulatory bodies increasingly demand eco-friendly products, companies that invest in recyclable and bio-based materials are likely to gain a competitive edge. Additionally, advancements in sealing technologies offer opportunities for innovation and improved product performance.
Emerging markets, particularly in Asia Pacific, present substantial growth opportunities due to rising consumer demand and expanding food industries. Companies that can establish a strong presence in these regions and adapt to local market needs are well-positioned to capitalize on this growth potential.
However, the market also faces threats from raw material price volatility and supply chain disruptions. Fluctuations in the prices of polymers and aluminum can impact production costs and profitability. Additionally, supply chain complexities and logistical challenges can affect the timely delivery of products to end-users.
Regulatory uncertainty and evolving sustainability requirements pose additional challenges for the market. Companies must navigate a complex regulatory landscape and adapt to changing requirements to remain compliant and competitive. Failure to do so can result in increased costs and potential market share loss.
Drivers & Challenges
One of the primary drivers of the Flexible Lid Stock Packaging market is the increasing demand for convenience foods and ready-to-eat meals. As consumers seek more convenient packaging solutions, the demand for flexible lid stock packaging, which offers ease of use and extended shelf life, is expected to rise. Additionally, the growing focus on sustainability and recyclability in packaging is pushing manufacturers to innovate with eco-friendly materials and technologies.
Another significant driver is the advancement in sealing technologies, such as ultrasonic and induction sealing, which enhance the functionality and integrity of flexible lid stock packaging. These technologies are gaining traction due to their ability to provide superior sealing performance, reduce material usage, and improve operational efficiency. As a result, manufacturers are investing in these technologies to gain a competitive edge and meet the evolving needs of end-users.
Despite these drivers, the market faces challenges related to raw material price volatility and supply chain disruptions. Fluctuations in the prices of polymers and aluminum can impact production costs and profitability. Additionally, supply chain complexities and logistical challenges can affect the timely delivery of products to end-users. Companies must navigate these challenges to maintain competitiveness and ensure sustainable growth.
Packaging Market Economics
The economics of the Flexible Lid Stock Packaging market are influenced by several factors, including raw material costs, conversion costs, and energy expenses. The prices of polymers, aluminum, and paperboard play a significant role in determining production costs. Additionally, conversion costs, including extrusion, lamination, and printing, impact the overall cost structure.
Energy costs are another critical factor, as they affect the operational efficiency of manufacturing processes. Companies must optimize energy usage to reduce costs and improve profitability. Logistics and distribution expenses also contribute to the overall economics, with efficient supply chain management being essential for cost-effective operations.
Packaging Value Chain & Cost Analysis
The value chain for Flexible Lid Stock Packaging involves several tiers, including resin synthesis, film extrusion, and converting. Resin synthesis and additive production form the foundation of the value chain, providing the necessary raw materials for film extrusion and paperboard production.
Film extrusion and paperboard mills are critical components of the value chain, as they produce the substrates used in lid stock packaging. Converting, printing, and lamination processes transform these substrates into finished products, ready for distribution and end-use.
Downstream activities, such as co-packing and distribution, play a crucial role in delivering products to end-users. Efficient logistics and supply chain management are essential for maintaining competitiveness and ensuring timely delivery. Additionally, end-of-life infrastructure, including recycling and sorting, is becoming increasingly important as sustainability becomes a priority for the industry.
Unit Economics & Substrate Cost Analysis
The unit economics of Flexible Lid Stock Packaging are influenced by several cost components, including raw material costs, energy expenses, and conversion costs. Raw material costs, particularly for polymers and aluminum, are a significant factor in determining the overall cost structure.
Energy expenses impact the operational efficiency of manufacturing processes, with companies striving to optimize energy usage to reduce costs. Conversion costs, including extrusion, printing, and lamination, also play a critical role in the unit economics, affecting the final product price and profitability.
Packaging Regulatory & Sustainability Analysis
The Flexible Lid Stock Packaging market is subject to various regulatory requirements and sustainability initiatives. Packaging regulations, such as the European Commission's directives on recyclability and extended producer responsibility (EPR), influence product design and material selection.
Sustainability initiatives, including the use of post-consumer recycled (PCR) materials and bio-based materials, are gaining traction as companies strive to meet consumer demand for eco-friendly products. Compliance with food-contact requirements and labeling regulations is also essential for market participants to ensure product safety and consumer trust.
Strategic Mergers, Acquisitions & Capacity Expansions
Recent strategic developments in the Flexible Lid Stock Packaging market include mergers, acquisitions, and capacity expansions by key players. Companies are pursuing these strategies to enhance their market position, expand their product portfolios, and increase production capacity.
For example, Amcor's acquisition of Bemis has strengthened its position in the flexible packaging market, providing access to new technologies and expanding its geographic presence. Similarly, Berry Global's acquisition of RPC Group has enhanced its capabilities in sustainable packaging solutions.
Capacity expansions, such as Mondi Group's investment in new production facilities, are aimed at meeting growing demand and improving operational efficiency. These strategic developments are expected to drive market growth and create new opportunities for innovation and differentiation.
Strategic Action Directives
Brand Packaging Engineers & Sustainability Directors: Focus on material selection and recyclability to meet sustainability goals. Consider mono-material qualification and PCR integration for enhanced environmental performance.
Converter Operations & Extrusion Leads: Optimize line speed and tooling to improve operational efficiency. Address PCR variability and capacity utilization to enhance production capabilities.
Procurement & Material Sourcing Managers: Diversify supplier base and secure resin contracts to mitigate price volatility. Explore price indexing and PCR contracts for cost-effective procurement strategies.
Investors: Monitor capacity expansions and M&A activities to identify growth opportunities. Evaluate market concentration and technology advancements for strategic investment decisions.
Market Share Analysis
The Flexible Lid Stock Packaging market is characterized by a competitive landscape with several key players vying for market share. Companies such as Amcor, Berry Global, and Constantia Flexibles are prominent players, leveraging their extensive product portfolios and global presence to maintain a competitive edge.
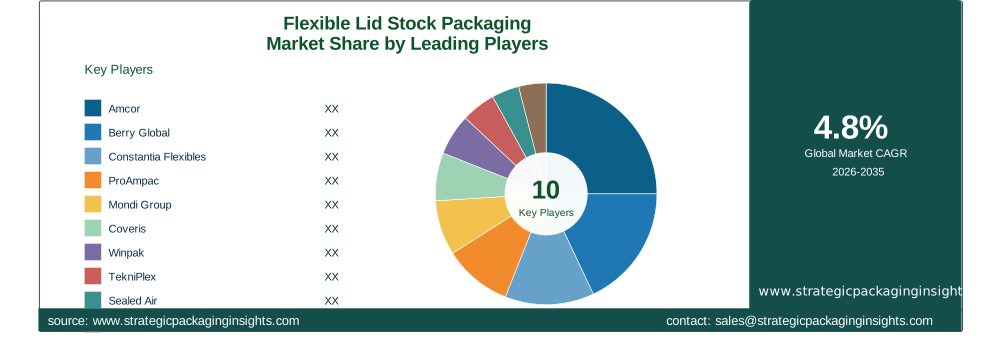
Amcor, with its acquisition of Bemis, has strengthened its position in the flexible packaging market, expanding its capabilities and geographic reach. Berry Global's acquisition of RPC Group has enhanced its focus on sustainable packaging solutions, aligning with market trends and consumer demands.
Constantia Flexibles is known for its innovative packaging solutions and strong focus on sustainability. The company's commitment to developing eco-friendly products has positioned it as a leader in the market, catering to the evolving needs of consumers and regulatory requirements.
Other notable players include ProAmpac, Mondi Group, and Coveris, each with their unique strengths and market strategies. ProAmpac's focus on innovation and customer-centric solutions has enabled it to capture market share and drive growth. Mondi Group's investment in capacity expansion and sustainable packaging solutions has positioned it as a key player in the industry.
Key Highlights
- Largest Region: North America
- Fastest-Growing Region: Asia Pacific
- Largest Segment: Food Packaging
- Fastest-Growing Segment: Recyclable Laminates
- Base-year market size: $8.7 Billion
- Forecast-year market size: $13.9 Billion
- CAGR: 4.8%
- Important application: Ready-to-Eat Meals
- Major end-use industry: Food and Beverage
- Major market driver: Demand for convenience foods
Regional Insights
The Flexible Lid Stock Packaging market is witnessing significant growth across major regions, with North America being the largest market and Asia Pacific emerging as the fastest-growing region. The demand for convenience foods and sustainable packaging solutions is driving market growth in these regions.
North America
North America is the largest market for Flexible Lid Stock Packaging, driven by the high demand for convenience foods and ready-to-eat meals. The region's focus on sustainability and recyclability is also contributing to market growth, with companies investing in eco-friendly packaging solutions.
The presence of key players such as Amcor and Berry Global further strengthens the market, as these companies continue to innovate and expand their product offerings. The region's well-established supply chain infrastructure and regulatory support for sustainable packaging are additional factors driving market growth.
Europe
Europe is a significant market for Flexible Lid Stock Packaging, with a strong emphasis on sustainability and regulatory compliance. The European Commission's directives on recyclability and extended producer responsibility (EPR) are influencing product design and material selection, driving demand for eco-friendly packaging solutions.
The region's focus on reducing packaging waste and promoting circular economy principles is encouraging companies to invest in sustainable materials and technologies. As a result, Europe is witnessing increased adoption of recyclable and bio-based materials in flexible lid stock packaging.
Asia Pacific
Asia Pacific is the fastest-growing region for Flexible Lid Stock Packaging, driven by rising consumer demand and expanding food industries. The region's growing middle-class population and increasing urbanization are contributing to the demand for convenience foods and ready-to-eat meals.
Companies are expanding their manufacturing capabilities in the region to cater to local market needs and capitalize on growth opportunities. The focus on sustainability and innovation is also driving market growth, with companies investing in eco-friendly packaging solutions to meet consumer preferences.
Latin America
Latin America is experiencing steady growth in the Flexible Lid Stock Packaging market, driven by the increasing demand for packaged foods and beverages. The region's focus on improving packaging infrastructure and adopting sustainable practices is contributing to market growth.
Companies are investing in capacity expansion and strategic partnerships to strengthen their market presence and meet the growing demand for flexible packaging solutions. The region's favorable regulatory environment and government support for sustainable packaging initiatives are additional factors driving market growth.
Middle East & Africa
The Middle East & Africa region is witnessing moderate growth in the Flexible Lid Stock Packaging market, driven by the demand for packaged foods and beverages. The region's focus on improving packaging standards and adopting sustainable practices is contributing to market growth.
Companies are exploring opportunities for expansion and innovation in the region, with a focus on developing eco-friendly packaging solutions to meet consumer preferences. The region's growing population and increasing urbanization are additional factors driving market growth.
By Material Analysis
The Flexible Lid Stock Packaging market is characterized by a diverse range of materials, each offering unique properties and benefits. Polyethylene (PE) and Polypropylene (PP) are widely used due to their excellent barrier properties and cost-effectiveness. Polyethylene Terephthalate (PET) and Polyamide (PA) are preferred for their high strength and durability, making them suitable for demanding applications.
Aluminum Foil and Paper and Paperboard are popular choices for their recyclability and sustainability, aligning with the growing demand for eco-friendly packaging solutions. Ethylene Vinyl Alcohol (EVOH) and Multi-Layer Laminates offer superior barrier properties, making them ideal for applications requiring extended shelf life and protection against moisture and oxygen.
The market is witnessing increased adoption of recyclable and bio-based materials, driven by regulatory pressures and consumer demand for sustainable packaging solutions. Companies are investing in research and development to enhance the performance and sustainability of these materials, creating new opportunities for growth and innovation.
By Lid Type Analysis
The Flexible Lid Stock Packaging market offers a variety of lid types, each designed to meet specific consumer needs and preferences. Peelable Lids and Resealable Lids are popular choices for their convenience and ease of use, particularly in the food and beverage industry. Heat-Seal Lids and Easy-Open Lids offer excellent sealing performance and are widely used in applications requiring extended shelf life and product protection.
Die-Cut Lids and Pressure-Sensitive Lids are gaining traction due to their versatility and ability to accommodate various packaging formats. These lid types are particularly popular in the dairy and ready-to-eat meals segments, where convenience and product integrity are critical factors.
The market is witnessing increased demand for innovative lid solutions that enhance consumer convenience and product functionality. Companies are investing in research and development to create new lid designs and technologies that meet evolving consumer preferences and regulatory requirements.
By Packaging Format Analysis
The Flexible Lid Stock Packaging market encompasses a wide range of packaging formats, each catering to specific consumer needs and product requirements. Cups, Trays, and Tubs are popular choices for their versatility and ability to accommodate various food and beverage products. Bowls and Containers offer excellent product protection and are widely used in applications requiring extended shelf life and convenience.
Pouches and Other Flexible Packaging Formats are gaining popularity due to their lightweight and space-saving properties, making them ideal for on-the-go consumption and e-commerce applications. The market is witnessing increased demand for innovative packaging formats that enhance consumer convenience and product functionality.
Companies are investing in research and development to create new packaging designs and technologies that meet evolving consumer preferences and regulatory requirements. The focus on sustainability and recyclability is driving the adoption of eco-friendly packaging formats, creating new opportunities for growth and innovation.
By Barrier Property Analysis
The Flexible Lid Stock Packaging market offers a variety of barrier properties, each designed to meet specific product protection and shelf life requirements. High Oxygen Barrier and Moisture Barrier properties are critical for applications requiring extended shelf life and protection against spoilage. Light Barrier and Aroma Barrier properties are essential for preserving product quality and freshness.
Gas Barrier and Standard Barrier properties offer versatile solutions for a wide range of applications, including food, pharmaceuticals, and personal care products. The market is witnessing increased demand for innovative barrier solutions that enhance product protection and consumer convenience.
Companies are investing in research and development to create new barrier technologies and materials that meet evolving consumer preferences and regulatory requirements. The focus on sustainability and recyclability is driving the adoption of eco-friendly barrier solutions, creating new opportunities for growth and innovation.
By Application Analysis
The Flexible Lid Stock Packaging market serves a diverse range of applications, each with unique requirements and challenges. Food Packaging is the largest segment, driven by the demand for convenience foods and ready-to-eat meals. Dairy Products and Meat and Seafood are significant applications, requiring packaging solutions that offer extended shelf life and product protection.
Ready-to-Eat Meals and Snacks are gaining popularity due to their convenience and ease of use, driving demand for flexible lid stock packaging. Pet Food and Pharmaceuticals are also important applications, requiring packaging solutions that meet strict regulatory requirements and consumer preferences.
The market is witnessing increased demand for innovative packaging solutions that enhance consumer convenience and product functionality. Companies are investing in research and development to create new packaging designs and technologies that meet evolving consumer preferences and regulatory requirements.
By Sealing Technology Analysis
The Flexible Lid Stock Packaging market offers a variety of sealing technologies, each designed to meet specific product protection and consumer convenience requirements. Heat Sealing is the most widely used technology, offering excellent sealing performance and versatility. Ultrasonic Sealing and Induction Sealing are gaining popularity due to their ability to provide superior sealing performance and reduce material usage.
Adhesive Sealing is a versatile solution for applications requiring resealability and convenience. The market is witnessing increased demand for innovative sealing technologies that enhance product protection and consumer convenience.
Companies are investing in research and development to create new sealing technologies and materials that meet evolving consumer preferences and regulatory requirements. The focus on sustainability and recyclability is driving the adoption of eco-friendly sealing solutions, creating new opportunities for growth and innovation.
By End Use Industry Analysis
The Flexible Lid Stock Packaging market serves a diverse range of end-use industries, each with unique requirements and challenges. The Food and Beverage industry is the largest end-use industry, driven by the demand for convenience foods and ready-to-eat meals. Pharmaceuticals and Healthcare are significant industries, requiring packaging solutions that meet strict regulatory requirements and consumer preferences.
Personal Care and Cosmetics, Pet Food, and Household Products are also important end-use industries, requiring packaging solutions that offer convenience and product protection. The market is witnessing increased demand for innovative packaging solutions that enhance consumer convenience and product functionality.
Companies are investing in research and development to create new packaging designs and technologies that meet evolving consumer preferences and regulatory requirements. The focus on sustainability and recyclability is driving the adoption of eco-friendly packaging solutions, creating new opportunities for growth and innovation.
By Sustainability Analysis
The Flexible Lid Stock Packaging market is witnessing a significant shift towards sustainability, driven by regulatory pressures and consumer demand for eco-friendly products. Conventional Laminates are being replaced by Recyclable Laminates and Mono-Material Films, which offer improved recyclability and reduced environmental impact.
Post-Consumer Recycled Materials and Bio-Based Materials are gaining traction as companies strive to meet sustainability goals and reduce their carbon footprint. Compostable Materials are also being explored as a viable alternative for applications requiring biodegradability and environmental compatibility.
The market is witnessing increased demand for innovative sustainable packaging solutions that enhance consumer convenience and product functionality. Companies are investing in research and development to create new materials and technologies that meet evolving consumer preferences and regulatory requirements.
By Distribution Channel Analysis
The Flexible Lid Stock Packaging market is characterized by a diverse range of distribution channels, each catering to specific customer needs and preferences. Direct Sales and Packaging Distributors are popular choices for their ability to provide customized solutions and personalized service.
Specialty Packaging Suppliers and Online Sales are gaining popularity due to their convenience and accessibility, particularly in the e-commerce sector. The market is witnessing increased demand for innovative distribution strategies that enhance customer convenience and product availability.
Companies are investing in research and development to create new distribution models and technologies that meet evolving consumer preferences and regulatory requirements. The focus on sustainability and recyclability is driving the adoption of eco-friendly distribution solutions, creating new opportunities for growth and innovation.
Flexible Lid Stock Packaging Market Segments
The Flexible Lid Stock Packaging market has been segmented on the basis ofBy Material
- Polyethylene (PE)
- Polypropylene (PP)
- Polyethylene Terephthalate (PET)
- Polyamide (PA)
- Aluminum Foil
- Paper and Paperboard
- Ethylene Vinyl Alcohol (EVOH)
- Multi-Layer Laminates
By Lid Type
- Peelable Lids
- Resealable Lids
- Heat-Seal Lids
- Easy-Open Lids
- Die-Cut Lids
- Pressure-Sensitive Lids
By Packaging Format
- Cups
- Trays
- Tubs
- Bowls
- Containers
- Pouches
- Other Flexible Packaging Formats
By Barrier Property
- High Oxygen Barrier
- Moisture Barrier
- Light Barrier
- Aroma Barrier
- Gas Barrier
- Standard Barrier
By Application
- Food Packaging
- Dairy Products
- Meat and Seafood
- Ready-to-Eat Meals
- Snacks
- Pet Food
- Pharmaceuticals
- Medical Products
- Personal Care Products
By Sealing Technology
- Heat Sealing
- Ultrasonic Sealing
- Induction Sealing
- Adhesive Sealing
By End Use Industry
- Food and Beverage
- Pharmaceuticals and Healthcare
- Personal Care and Cosmetics
- Pet Food
- Household Products
- Industrial Products
By Sustainability
- Conventional Laminates
- Recyclable Laminates
- Mono-Material Films
- Post-Consumer Recycled Materials
- Bio-Based Materials
- Compostable Materials
By Distribution Channel
- Direct Sales
- Packaging Distributors
- Specialty Packaging Suppliers
- Online Sales
By Region
- North America
- Europe
- Asia-Pacific
- Latin America
- Middle East and Africa